Why the 50-30-20 rule starts with a boundary
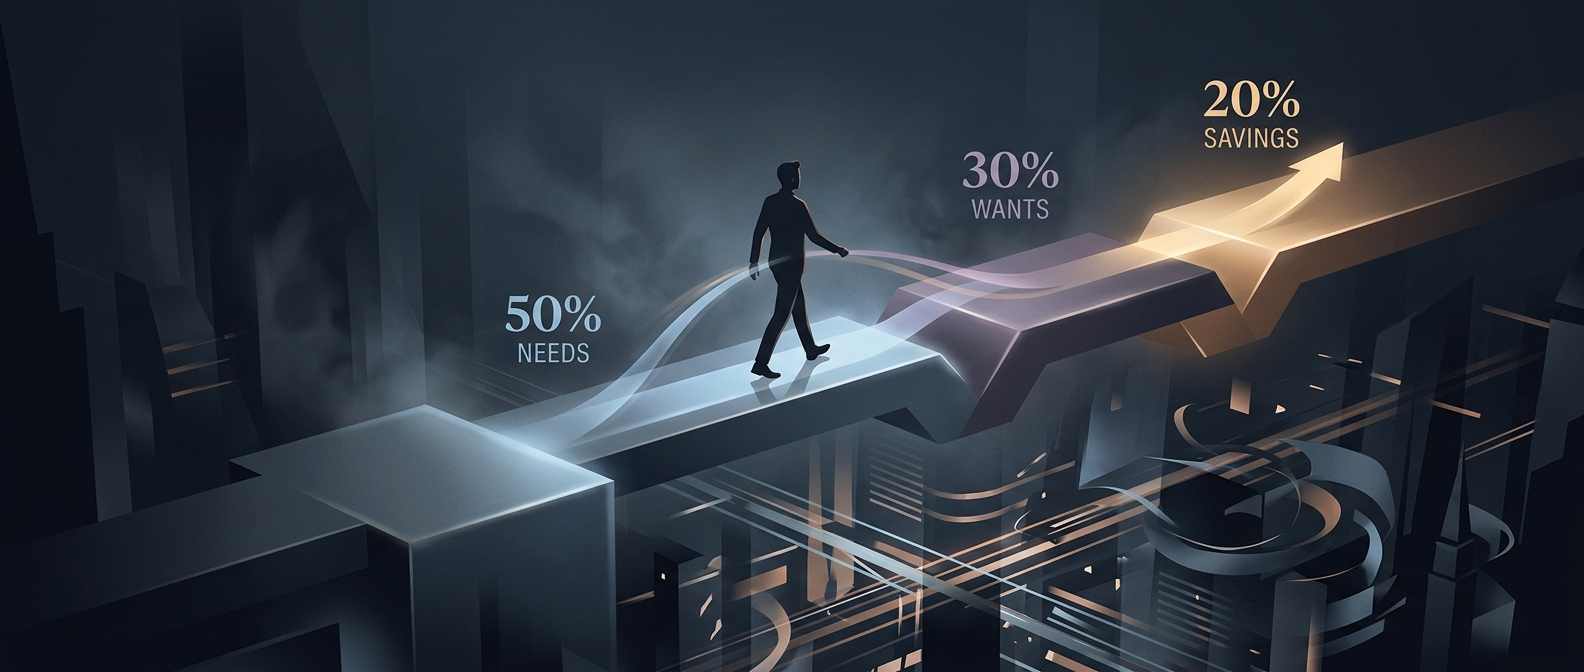
A budget is easier to follow when it separates spending by purpose, not just by merchant or account. The 50-30-20 rule gives each dollar of take-home pay a job: essentials, discretionary choices, or future financial obligations. That distinction can expose a problem a bank balance hides—for example, a month may feel affordable while rent and other fixed bills leave little room for saving.
“Needs” are expenses that are difficult to avoid, such as housing, basic utilities, groceries, and necessary transportation. “Wants” are more adjustable: dining out, subscriptions, or upgrades. The dividing line is sometimes personal. A car payment may be essential for someone who must drive to work, while a more expensive model or optional features are choices within that need.
The percentages are a diagnostic, not a verdict
The rule’s value is not that every household can fit neatly into the same proportions. Housing costs, family responsibilities, location, and income can make the needs share much higher than half. Treating the targets as a rigid test can make a useful budget feel like a failure; treating them as a starting point turns them into a way to see where money is going and which category can realistically change.
That flexibility also helps clarify what counts as progress. The savings share can build an emergency reserve or fund longer-term goals; paying down debt can reduce future interest costs and free up income later. Those uses compete in the short term, so the right priority depends partly on the debt’s cost and whether a basic cash cushion is already in place.
Make the plan fit the pay cycle
A percentage budget works best when it is translated into amounts for each payday and checked against actual bills. If essentials take more than the guideline allows, the useful question is whether a large cost can be changed over time—not whether groceries or rent can be wished away. If wants are absorbing the difference, naming that category makes tradeoffs visible without labeling every pleasure irresponsible.
The practical payoff is a clearer choice before the money disappears into routine spending: which costs are fixed, which are optional, and what portion should remain available for the next surprise.