How a bank’s failure travels through the network
Banks are connected by more than the loans customers take out. They lend to one another, trade financial contracts, and rely on other institutions to settle payments. These links make routine business possible, but they also create a route for losses to travel.
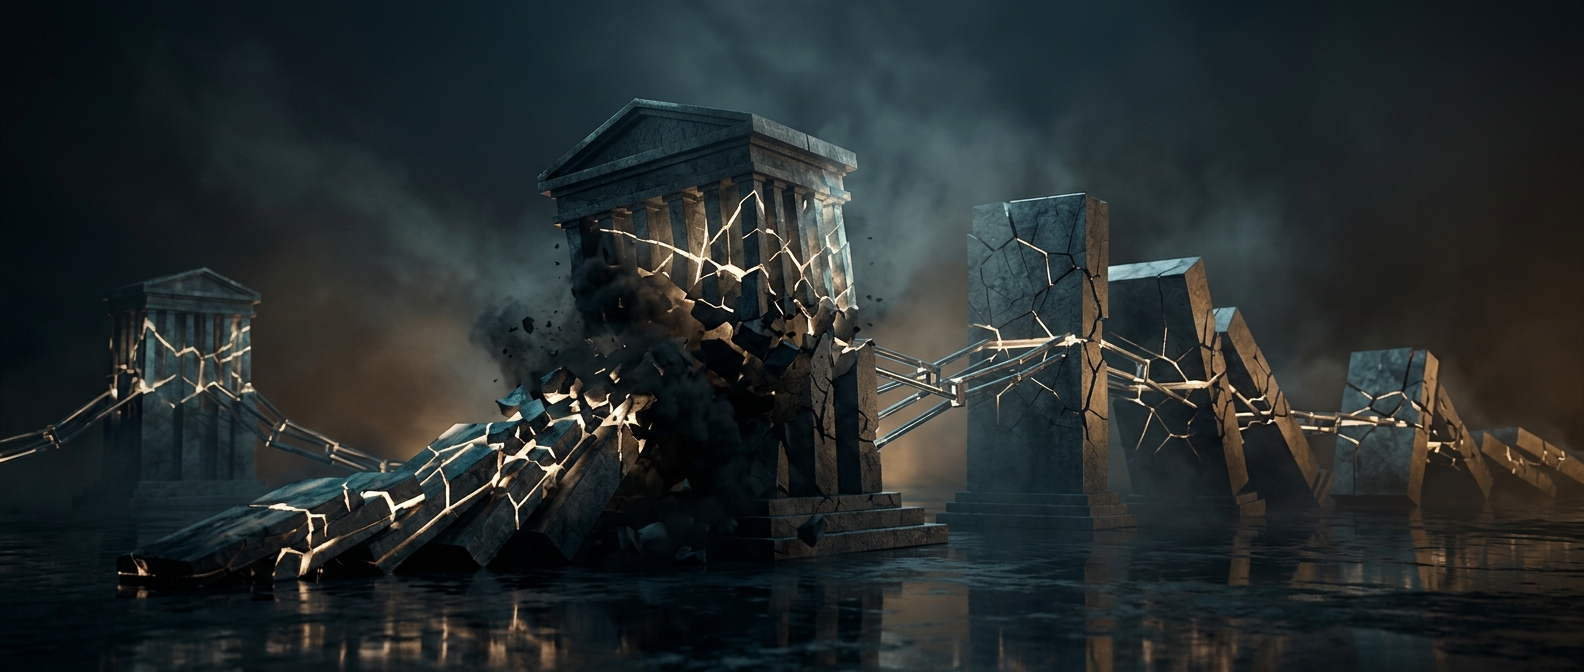
If a bank fails to deliver cash or assets it owes, a partner may have to replace that funding quickly or absorb a loss on the contract. The partner’s own finances then tighten. If it responds by delaying payments, cutting lending, or selling assets, the strain can reach still more institutions. The danger is not simply one bank’s bad assets; it is the uncertainty those losses create about who will be paid.
Why a shock can spread beyond direct losses
Even banks with limited direct exposure may pull back when they cannot tell which institutions are vulnerable. They may refuse to lend, demand more collateral, or hold on to cash. That caution can make it harder for otherwise sound banks to meet immediate obligations. Meanwhile, forced asset sales can push prices down, causing other banks that own similar assets to record losses too.
This chain is not automatic. Capital provides a cushion against losses, and safeguards such as deposit protection and emergency lending can help contain panic or temporary cash shortages. But those measures cannot instantly make every institution’s obligations clear. When confidence breaks and funding links seize up, a problem that began with one bank can become a broader credit squeeze—leaving businesses and households facing loans that are harder to get or more expensive.