Why Random Stock Picks Can Beat the Experts
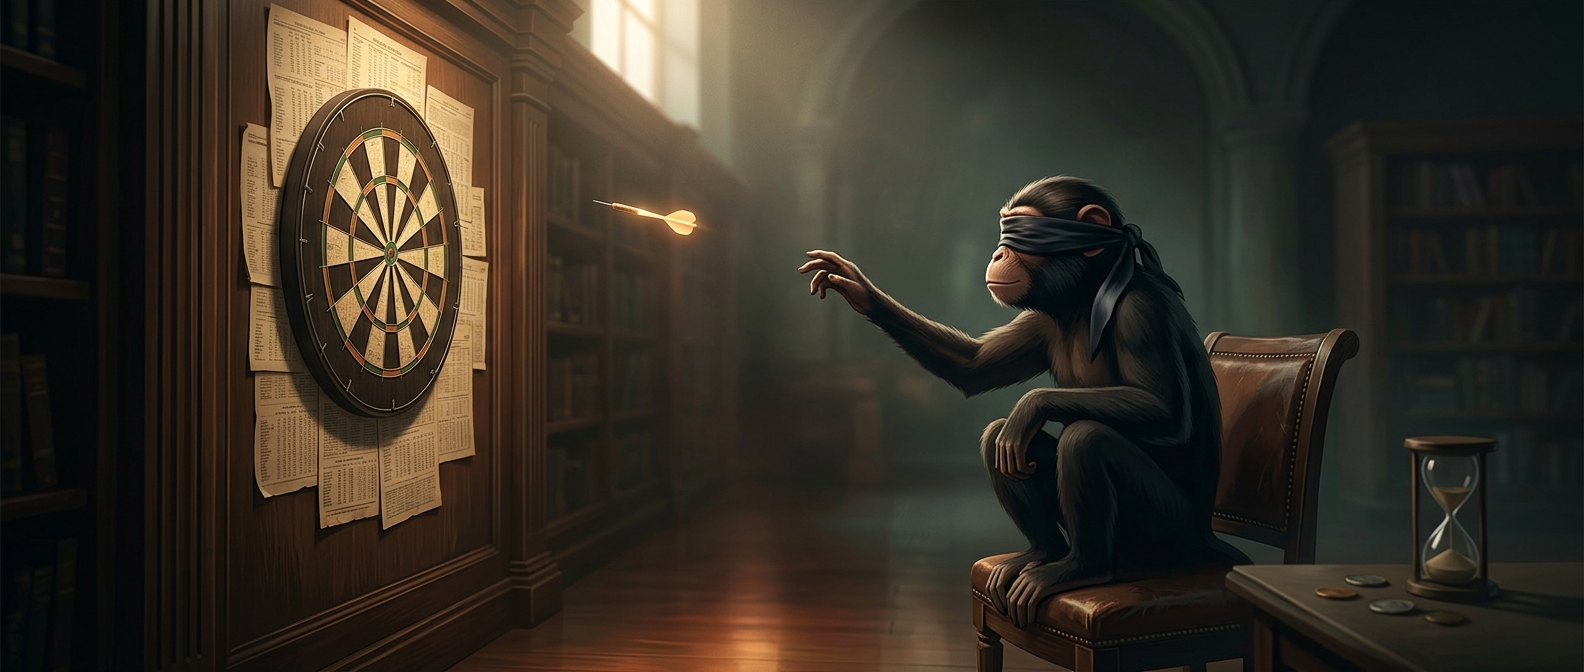
A dartboard is not a forecasting tool. The point of the monkey-and-darts comparison is that, over a limited stretch, a random portfolio can outperform a carefully chosen one—not that chance reliably identifies tomorrow’s winners. Stock prices move for reasons investors cannot fully anticipate, and short-term returns contain plenty of noise. That makes a professional’s informed choice difficult to distinguish from a lucky one after the fact.
In the 1973 challenge, economist Burton Malkiel used the image of a blindfolded monkey throwing darts at stock listings to make this point about stock picking. Later comparisons using darts or random-number selections sometimes found that random portfolios beat hedge fund managers. Such results depend on the stocks, time period, and benchmark being compared; they do not show that every manager loses or that a random strategy wins consistently.
The Costs Behind the Contest
A fair comparison must account for more than which portfolio had the higher return. A manager may charge fees, trade frequently, or take risks that differ from those of the random portfolio. And a portfolio that wins in one period may lose in another. A run of success can reflect skill, luck, or a mix of both; the results alone do not settle which.
This is one reason investors compare active funds with broad market indexes, which hold many stocks rather than relying on a manager to select a small set of winners. An index does not need to predict which company will surge. It spreads exposure across the market and avoids many of the costs of frequent selection. The striking implication of the dartboard is not that expertise is worthless, but that beating a simple, low-cost alternative is a tougher test than making a few good picks.