Why an Insurer Would Send Its Own Firefighters
A home insurance policy transfers some of a property's financial risk to the insurer. If a house burns, the company may have to pay a large claim. That gives the insurer a reason to spend money before a fire reaches the house: a private crew can cost less than rebuilding an insured estate.
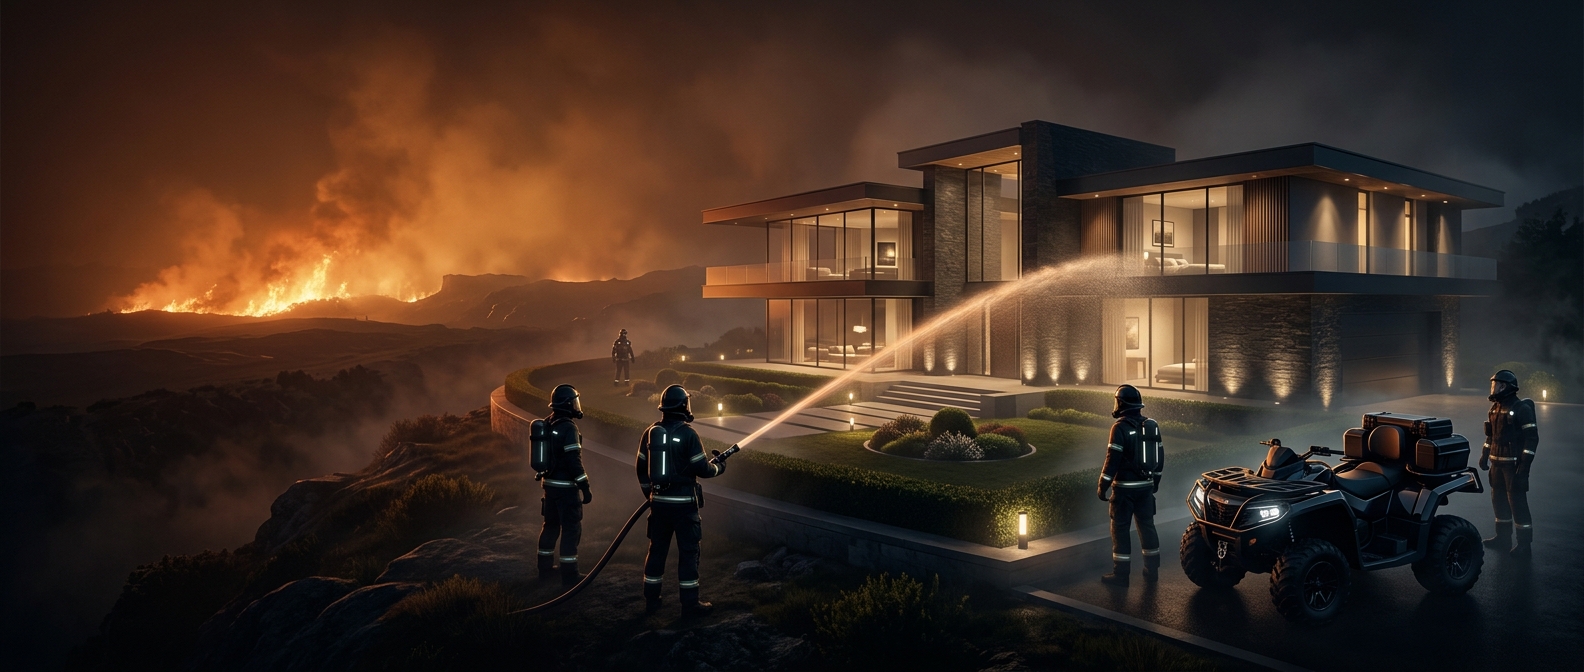
These crews are hired to protect particular properties, not to take over a public fire department’s job. Depending on conditions, they may prepare a site, watch for windblown embers, or try to keep flames from reaching the insured home. Their work is a form of loss prevention: intervene early in the hope of avoiding a much larger bill later.
The Client Is the Insurer
The unusual part is who pays. The property owner is the person at risk, but the insurance company may arrange and fund the protection because it stands to bear much of the financial loss. The service can be especially attractive where a high-value home would be costly to replace.
That logic also sets a limit. A private crew is there to defend the properties it has been assigned to protect; it is not a general emergency service for everyone nearby. Public firefighters, by contrast, have broader responsibilities, including protecting people and communities. Private crews may therefore add capacity at a threatened estate without solving the larger problem of limited firefighting resources.
Protection Follows the Policy
This arrangement reveals how insurance can shape emergency response: the insurer’s potential payout helps determine where extra resources go. A defended home may avoid severe damage, and the insurer may avoid a costly claim. But the same system directs special protection toward insured assets, not necessarily toward the places with the greatest public need. The crew’s presence is both a fire-response measure and a financial decision.