The economics of a barrier that can be bypassed
A border wall is a fixed investment: governments pay to build it, then keep spending on upkeep, repairs, access roads, and the people and equipment needed to monitor it. Its economic case therefore depends not on whether it blocks some crossings, but on whether the crossings it prevents are worth more than the full cost of installing and operating the barrier.
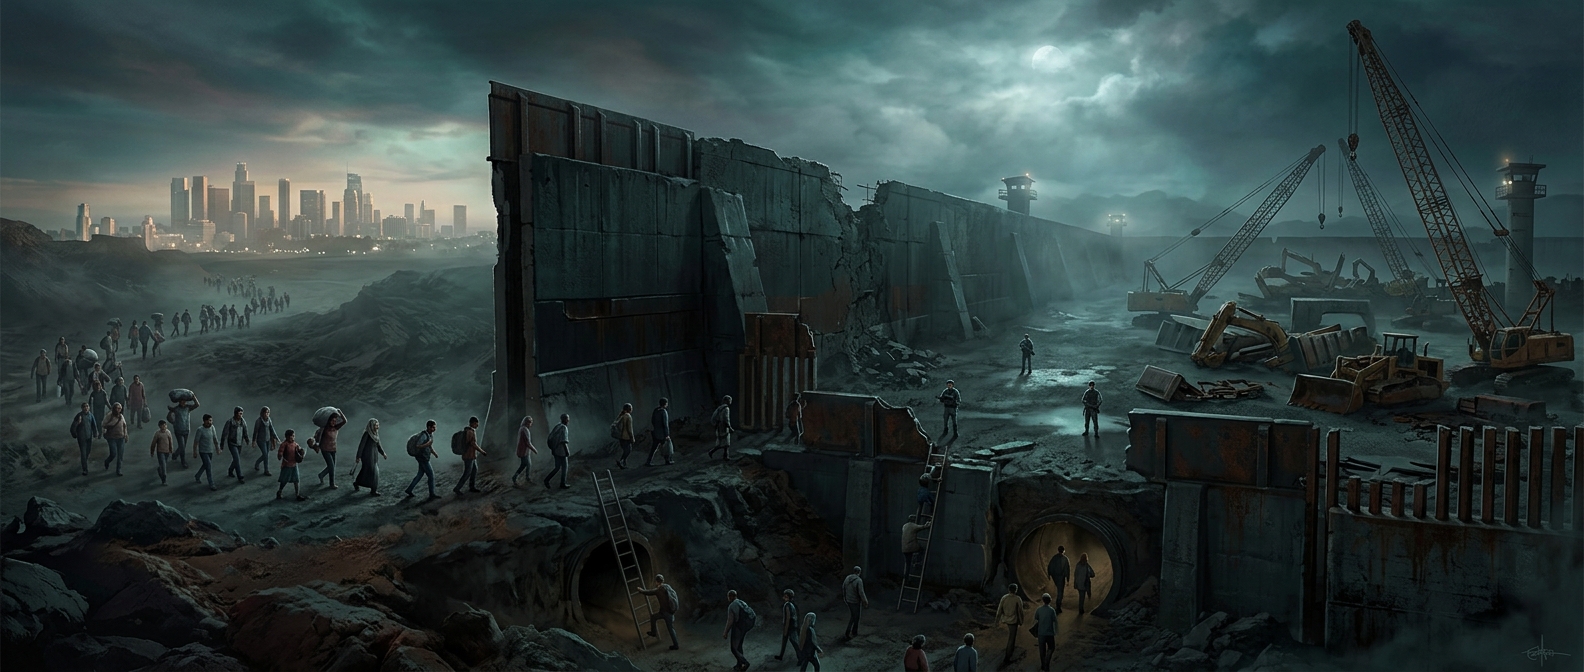
That calculation is difficult because a wall does not act alone. People may try another route, use a ladder or tunnel, or wait for a less guarded stretch. If crossings shift rather than stop, the barrier can change where enforcement is needed without reducing the underlying demand to cross. The government may then face added costs for patrols or replacement infrastructure elsewhere.
The benefit depends on what happens next
A wall can still have value if it slows movement enough for officers to respond, or if it discourages a meaningful number of attempts. But those benefits must be compared with alternatives, such as targeted staffing or surveillance, which may address particular crossing points without constructing a continuous barrier. The best choice depends on local terrain, traffic, and how people adapt—not on the wall’s length alone.
The costs and benefits also fall on different people. Public budgets pay for construction and maintenance; communities near the border may experience changes in access, land use, or enforcement. Meanwhile, any deterrence benefit is harder to measure than the visible structure itself. The key economic question is whether the wall prevents crossings, or mainly makes them more expensive to manage. That distinction is what turns a concrete barrier into a cost-benefit decision.