Why Norway’s oil money goes abroad
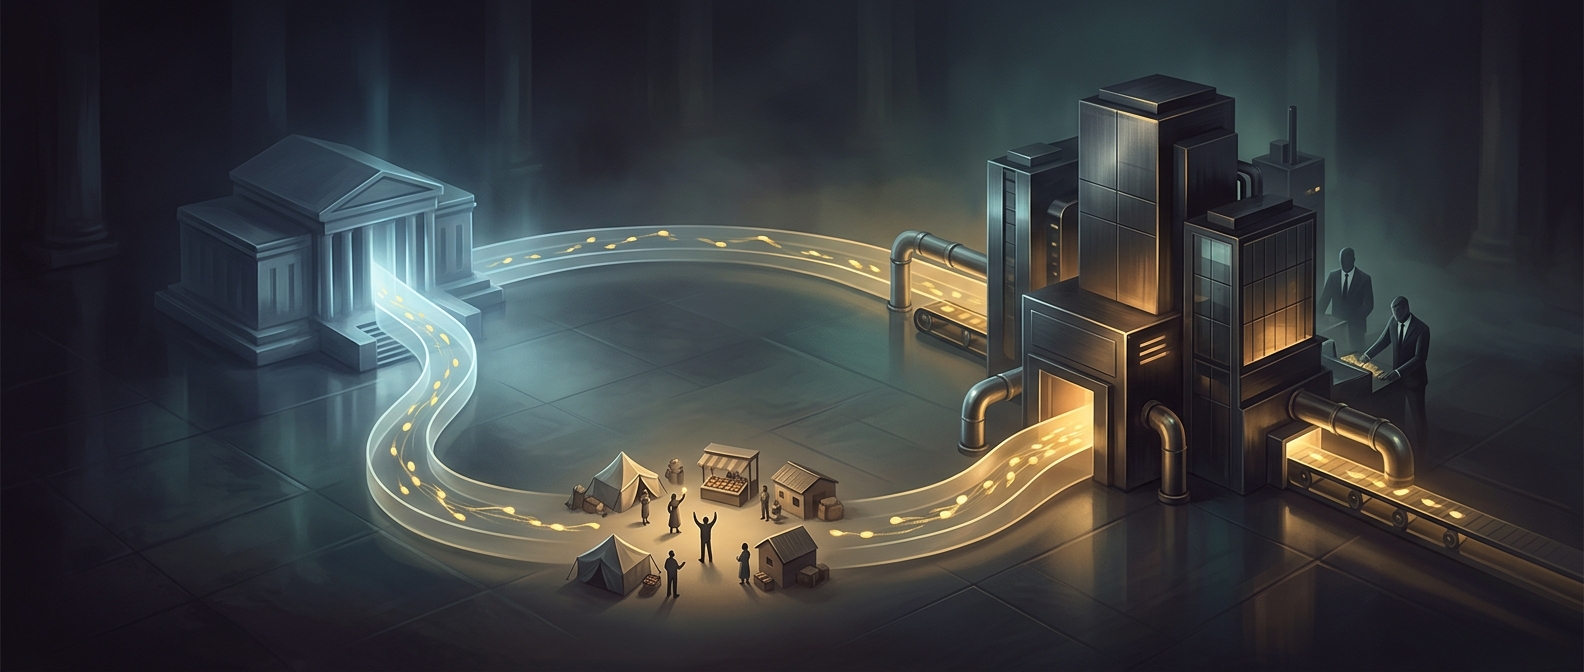
Oil revenue can arrive much faster than a country can usefully spend it. If a government pours a sudden windfall into domestic projects and wages, demand may rise faster than local businesses can supply goods and workers. Prices and costs can climb, and industries unrelated to oil may struggle to compete. Economists often call this pressure the “resource curse”: a natural resource brings wealth, but managing the windfall badly can leave the wider economy less resilient.
Norway’s response was to channel state petroleum income into a fund invested largely in foreign stocks, bonds, and property. Investing overseas helps keep the oil cash from flooding the home economy all at once. It also spreads the country’s exposure across many companies and markets, rather than tying its future only to oil prices or the health of Norwegian businesses.
A budget rule, not a locked vault
The fund is not a literal account whose principal can never be touched. Its value rises and falls with global markets, and the government can transfer money from it to help pay the national budget. The key restraint is a fiscal rule: over time, withdrawals are meant to track the fund’s expected long-term real return—the growth left after inflation—rather than the much larger balance itself.
That distinction matters. Spending the balance would turn a temporary resource windfall into a short-lived burst of public spending. Limiting withdrawals instead aims to preserve wealth that can support public services after oil production declines, while still allowing the budget to use some of the fund’s gains. The rule is a guide for responsible budgeting, not a promise that every year’s withdrawal exactly equals that year’s investment earnings.
Turning a finite resource into a lasting asset
The arrangement also makes the tradeoff visible: each budget decision about how much to withdraw is a decision about how much wealth remains invested for the future. Norway’s oil is extracted once; a diversified portfolio can continue producing income across generations. That is why the most consequential part of the policy is not simply saving the windfall, but making the annual budget live within a limit tied to the fund’s long-term earning power.