A tax that used windows as a proxy for wealth
In 1696, the English government adopted a window tax: instead of measuring a household’s income or fortune directly, it used the number of windows in a home as a visible clue to its owner’s means. Larger houses generally had more windows, making them easier to tax more heavily than modest homes. Counting openings was also simpler for officials than inspecting private finances.
The proxy had an obvious weakness: a window was not just evidence of wealth. It was part of a building’s usefulness. Once an extra opening increased the tax bill, owners had a reason to cover or remove it—even when the room behind it still needed daylight and fresh air.
The cost could reach tenants
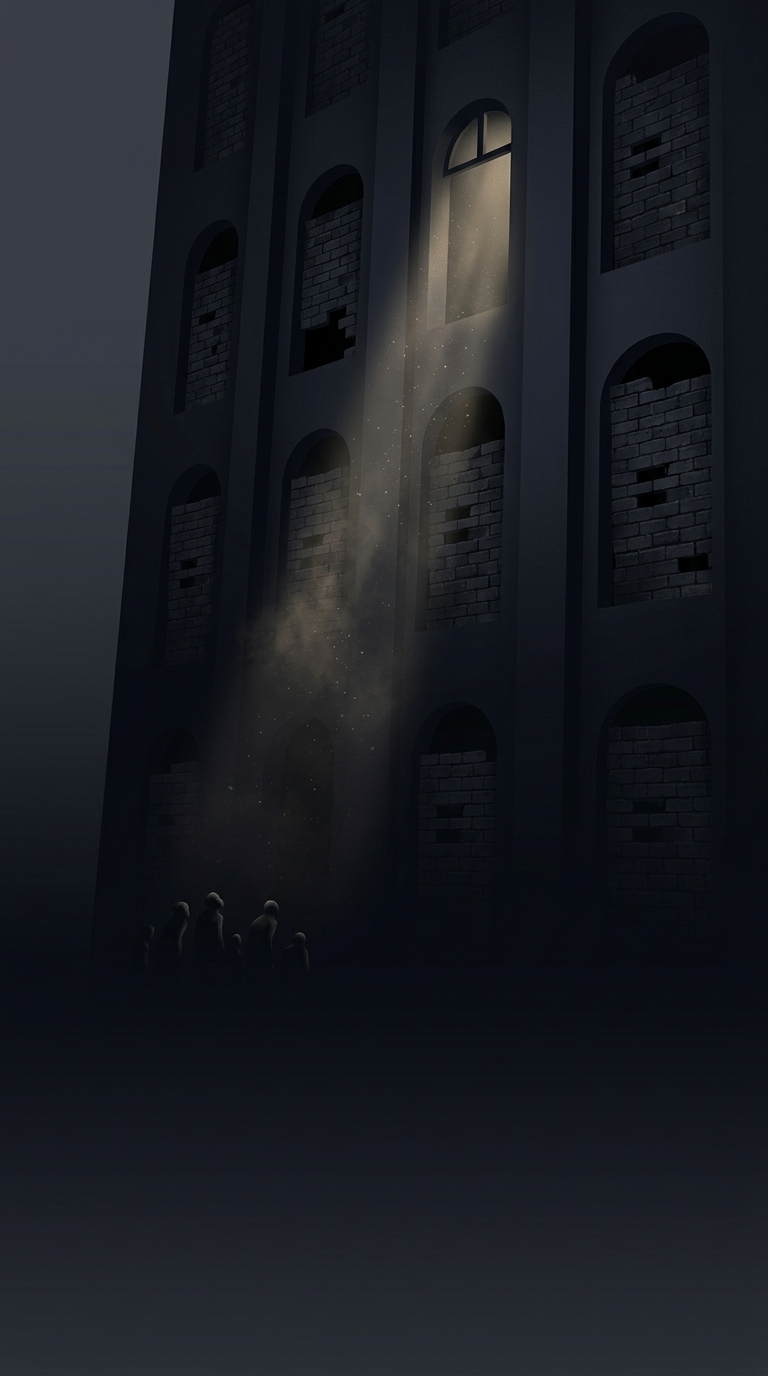
Blocking a window was a direct way to reduce the count on which the bill was based. The response altered the building itself: brick or other material could seal an opening, leaving rooms darker and less ventilated. In crowded rental housing, tenants might bear the consequences even though the property owner made the decision to avoid tax.
That gap between who chose and who suffered is central to the tax’s legacy. A levy aimed at property owners could affect the conditions experienced by people who had little control over the building. The incentive was especially perverse because it rewarded making a home less livable rather than making its owner’s finances easier to assess.
When the measure becomes the target
The window tax illustrates a recurring problem with indirect taxes: once a convenient stand-in for wealth determines the bill, people can change the stand-in. A window count was observable, but it could be manipulated by altering the house. The tax’s most literal escape route was also a lasting physical cost: fewer openings meant less light and air inside.