The business case for feeding the yard cats
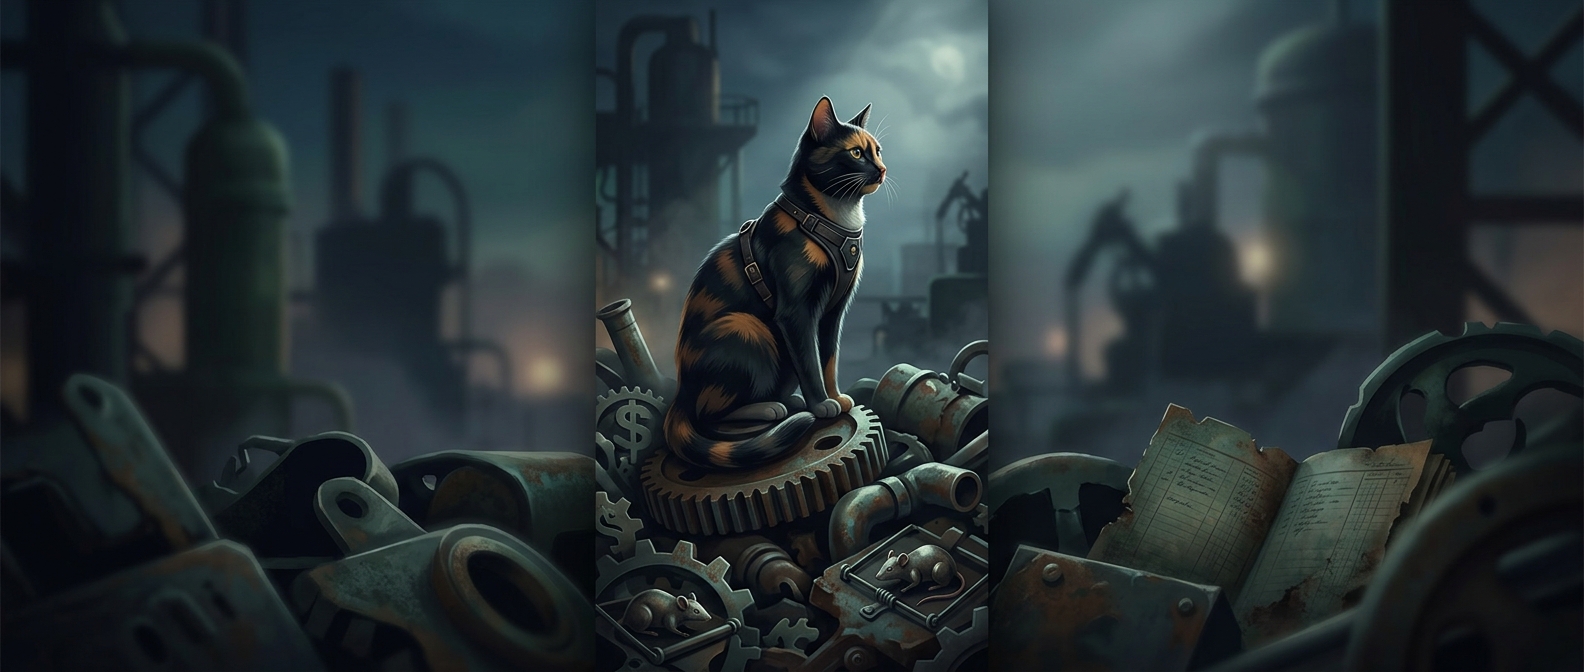
A scrap yard can attract rodents, and rodents can damage materials, spread contamination, or make a worksite less manageable. Cats that live around the yard may hunt them. An owner who buys food for those cats can therefore see the expense as part of keeping the property in working order—not simply as a personal pet expense.
That reasoning is the heart of the attempted deduction: if feeding the cats helps protect the business, perhaps the cost belongs among its operating expenses. But a plausible business benefit does not automatically make a purchase deductible.
Where the tax question turns
Tax treatment generally depends on the expense’s connection to the business and the facts surrounding it. Food bought for animals maintained to serve a business purpose may be easier to distinguish from food bought for pets kept for personal enjoyment. In practice, the owner would need to show that the cats’ role was genuinely tied to the yard rather than just asserting that they were useful.
That distinction can be awkward with feral cats. They may patrol the property without being owned, trained, or managed like conventional working animals. The same bag of food could look like a practical pest-control cost to one owner and a personal or charitable choice to another, depending on the circumstances and records.
A small expense, a larger principle
The cats turn an ordinary purchase into a question about how businesses draw the line between operating costs and private spending. The lesson is not that cat food is automatically deductible, but that an expense’s purpose matters—and that a colorful business explanation still has to fit the tax rules and be supportable.