Why a solvent bank could still run short of cash
A bank does not keep every customer’s deposit in a pile of cash behind the counter. It uses much of that money to make loans and hold other assets, which may be valuable but cannot always be turned into cash immediately. That arrangement lets banks finance homes, businesses, and other spending—but it creates a timing problem when many customers want their deposits at once.
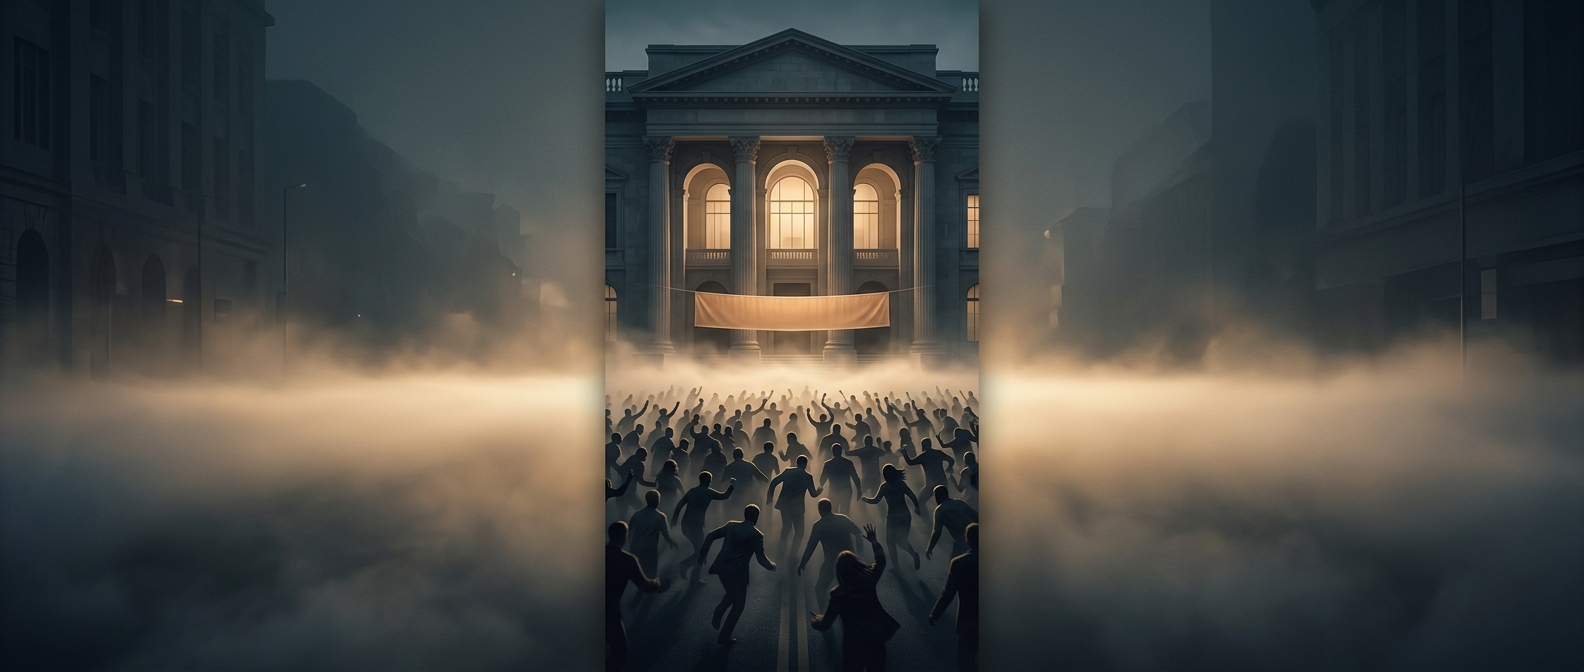
A withdrawal by itself may be manageable. A crowd can make the problem worse: seeing others queue for cash, customers may fear they will be last and rush to withdraw too. Even a bank with assets worth more than its debts can fail if it cannot convert those assets into cash fast enough.
A closure interrupted the rush
Temporarily shutting a bank’s doors stopped the immediate queue and bought time. It did not, by itself, create money or prove the bank was sound. The pause gave banks and public authorities an opportunity to assess which institutions could meet their obligations and how operations could resume.
That distinction mattered during the Great Depression. A closure could prevent a panic from draining cash in a few days, but it also left customers unable to access their money while the doors were shut. Reopening helped only if people believed the bank could honor withdrawals; otherwise, the same fear could start another rush.
The measure addressed a crisis of timing and confidence, not just a shortage of wealth. When customers’ decisions depend on what everyone else will do, keeping a bank closed briefly can be less damaging than letting a queue decide who gets paid first.