Why a fortune can grow faster than a tax bill
The key distinction is between wealth and taxable income. A worker generally owes income tax on wages when they are paid. A person who owns shares may become much richer as their value rises, but that increase is usually not taxed as income until the shares are sold. Until then, the gain exists on paper rather than as cash from a completed sale.
That difference matters because fortunes can grow mainly through ownership. If a company’s stock climbs, its owner’s net worth rises even if the owner receives little salary. Tax calculations that compare income taxes paid with wealth growth can therefore show a much lower rate for the owner than a wage earner’s rate on a paycheck.
Turning shares into spending money
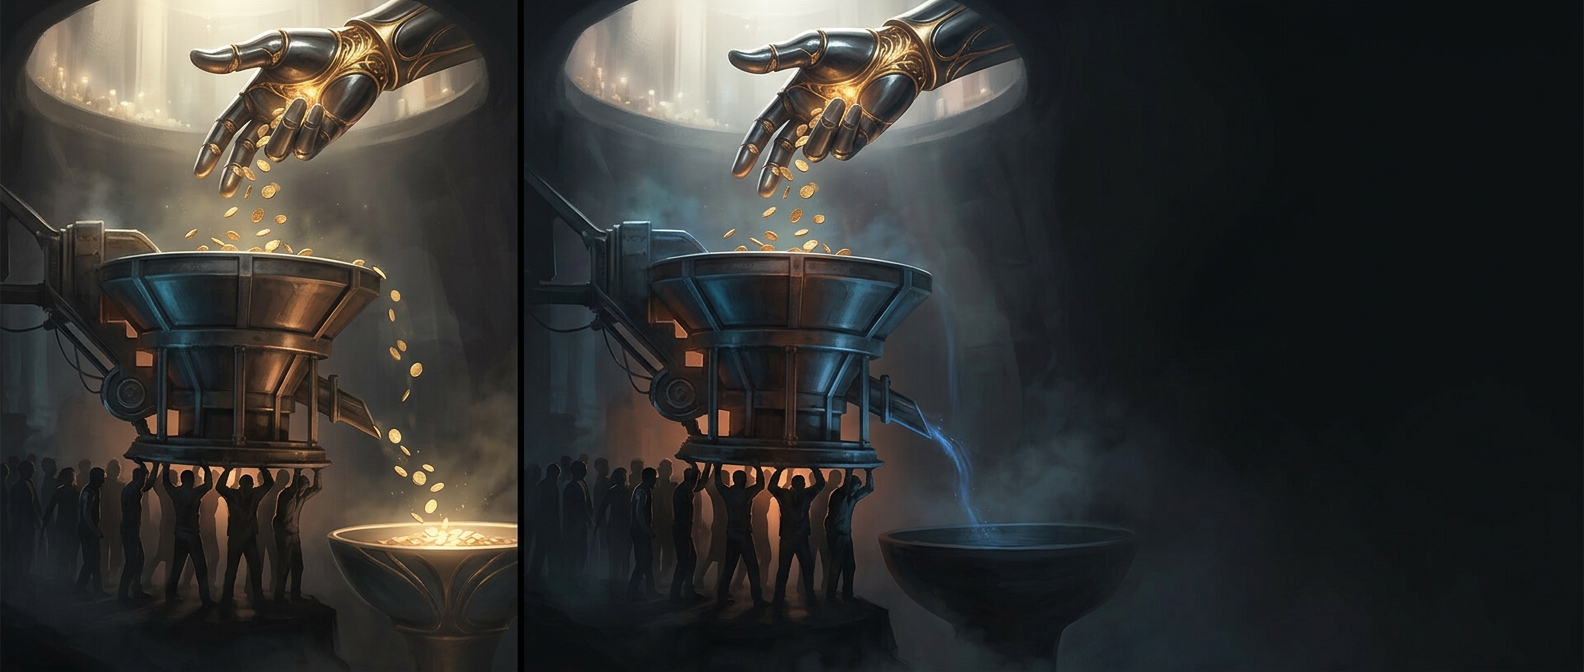
Selling stock would convert some of its value into cash, but it can also trigger tax on the gain. Instead, an owner can pledge shares as collateral for a loan. The lender provides cash, while the borrower keeps the shares and owes the money back. A loan is not generally treated as income because it comes with a repayment obligation, so receiving the cash does not itself create an income-tax bill.
This strategy does not make the debt disappear. The borrower pays interest, and a steep fall in the shares’ value can leave the lender demanding more collateral or repayment. Still, borrowing can provide spending money while allowing the owner to avoid selling shares—and postponing the tax that a sale could bring.
Why the comparison persists
The result is a mismatch between how different people get economic value and when the tax system recognizes it. Paychecks are visible and taxable as they arrive; rising stock values can remain untaxed while they are held. For someone whose wealth is concentrated in appreciating assets, the timing of a sale can shape the tax bill as much as the size of the fortune. A large increase in wealth does not necessarily produce a similarly large taxable income for that year.