How selling can become its own evidence
A financial model turns assumptions—about earnings, risk, or how prices usually behave—into an estimate. But during a panic, investors are not reacting only to those underlying numbers. They are also reacting to what they think other investors will do next.
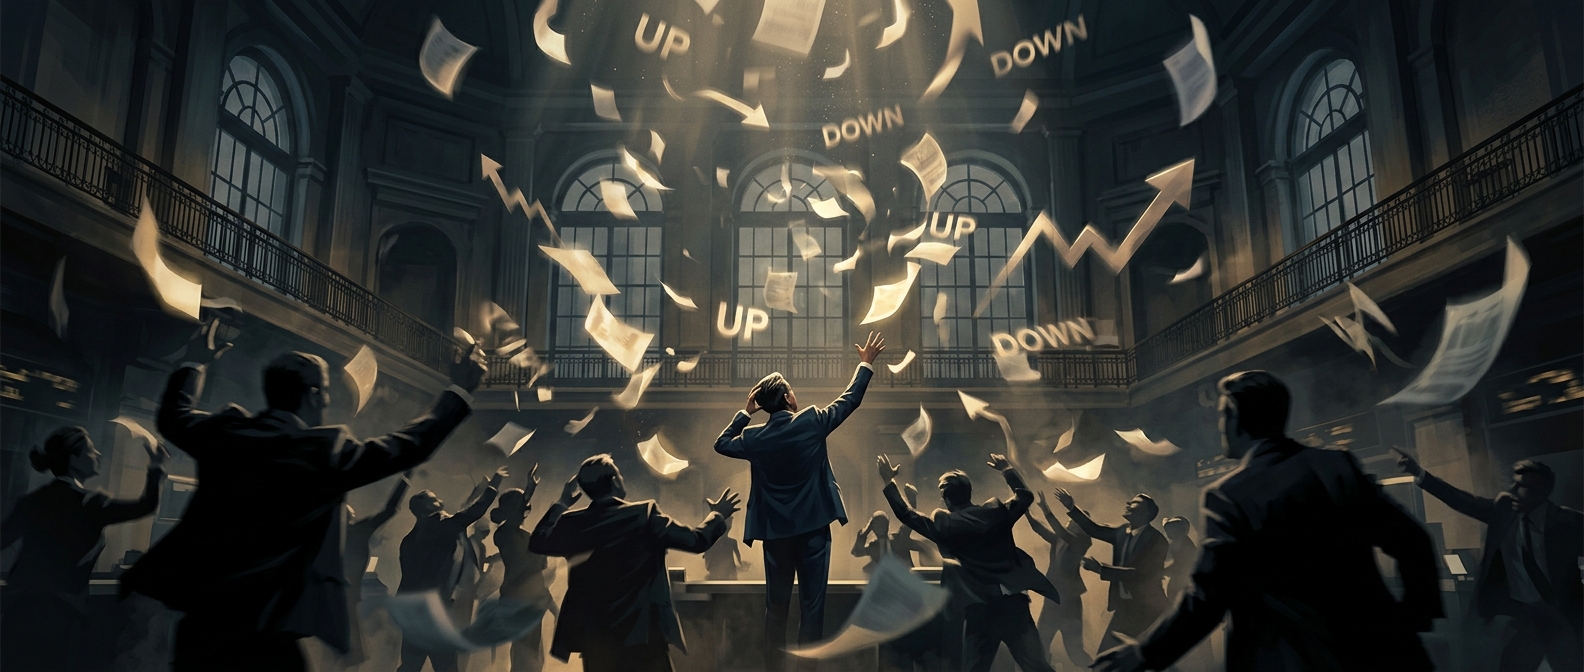
That creates a feedback loop. A fund sells to limit losses; the falling price worries other holders, who sell too. Their orders push prices lower, making the original fear look justified. In that moment, a visible price drop can feel more urgent than a model’s estimate of what an asset is worth.
Why fear can travel faster than analysis
Investors often have limited time and incomplete information. Watching others sell offers a quick, if imperfect, signal: perhaps they know something, or perhaps it is safer to leave before everyone else does. Even investors who believe an asset is undervalued may sell if they expect further losses or need cash to meet obligations.
This is especially consequential when many investors follow similar strategies or face similar constraints. A risk limit, margin call, or rush to raise cash can force sales regardless of anyone’s long-term view. The resulting price movement can then trigger more selling elsewhere.
What the formulas can miss
Models are useful maps, not guarantees. They depend on assumptions about how markets behave, and a model built from ordinary conditions may not capture what happens when many people act together. In a crisis, relationships that usually seem manageable—between prices, risk limits, and available buyers—can change quickly.
Fear does not make valuation irrelevant; it changes the forces acting on prices in the short run. A company’s prospects may remain intact while its shares plunge, but investors who must sell cannot necessarily wait for that distinction to matter. That is how a temporary rush for the exit can move a market farther, and faster, than the underlying news alone would suggest.