Why a donation’s path is not a straight line
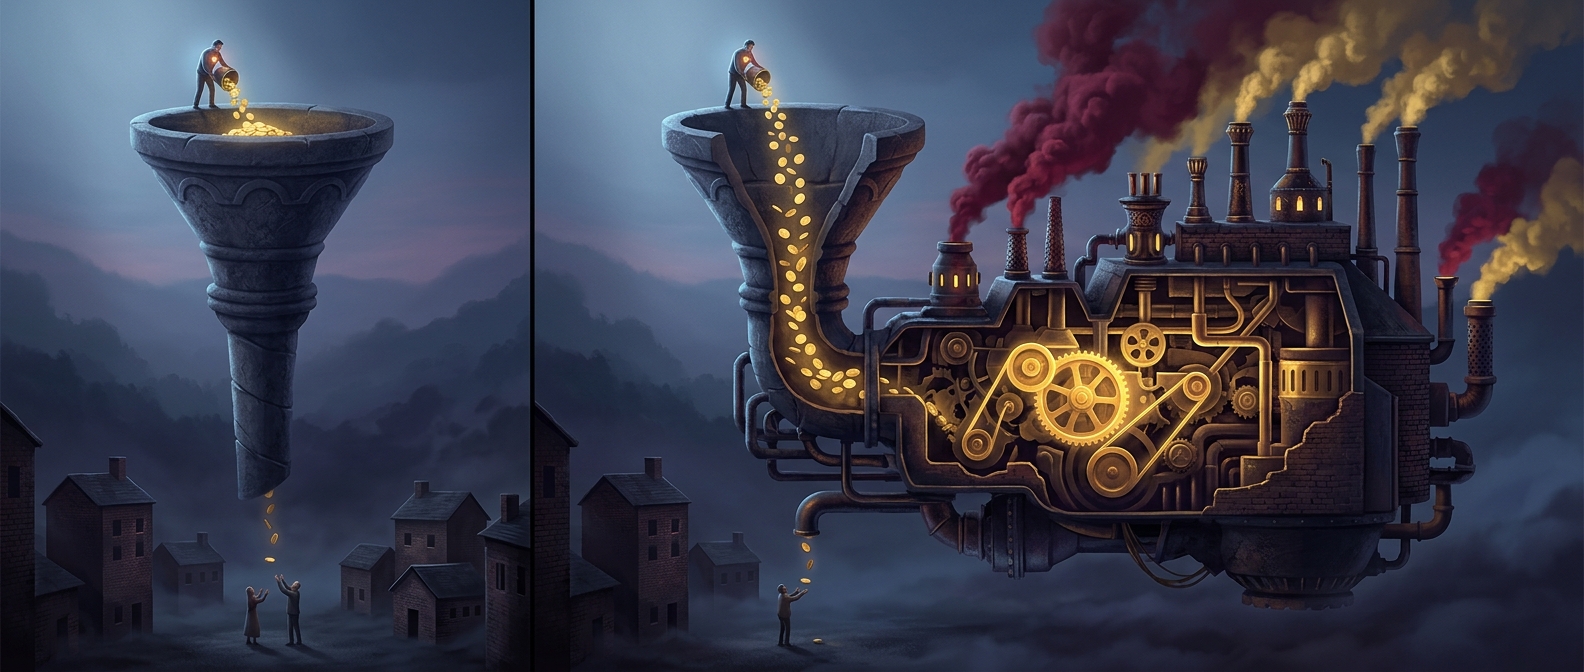
A gift rarely travels directly from a donor to a person receiving help. Organizations need people and systems to find beneficiaries, deliver services, track spending, and report results. Those costs may include staff, rent, payment processing, fundraising, and administration—the work that makes aid possible but is not itself direct aid.
That creates a useful distinction: a low overhead share does not automatically mean a charity is more effective. Cutting coordination or experienced staff can leave an organization less able to deliver help reliably. Conversely, high spending on fundraising may bring in enough additional donations to support more work overall. The important question is what the spending enables, not just how it is labeled.
The same gift can be counted in different ways
“Program expenses” generally refers to costs tied to an organization’s stated work, while fundraising and administrative costs are reported separately. But some work serves more than one purpose. A staff member might both deliver a service and manage the program; accounting rules require those costs to be allocated among categories. That means reported percentages are summaries, not a literal map of each donated dollar.
A donor can also make a restricted gift—one intended for a specified program or purpose. Such a gift is not interchangeable with unrestricted money, which the organization can use where needed. Even when a donation is restricted, supporting the program may require coordination and administration.
What to look for beyond a percentage
To judge whether a donation is likely to make a difference, consider what the organization does, whether its spending supports that work, and how clearly it explains its results and finances. The practical tradeoff is not “overhead or impact”: it is whether the costs behind the scenes help turn a promise of aid into aid that can actually be delivered.