A donation needs a system to reach its destination
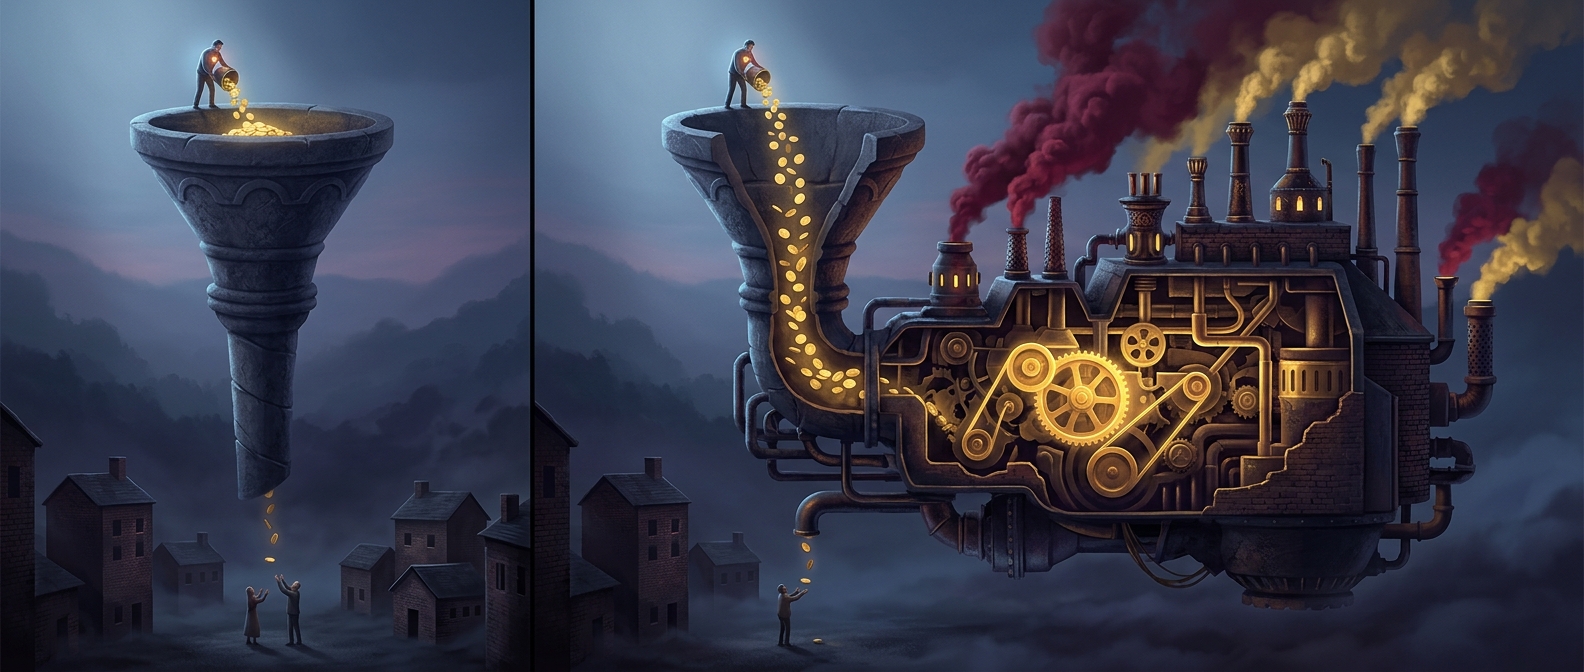
A charity’s work depends on more than the supplies or services donors picture. Staff must recruit and train people, keep records, coordinate schedules, maintain equipment, and make sure programs meet legal and safety requirements. These expenses are often grouped under overhead: the costs of running the organization rather than delivering a particular service directly.
The boundary is not always clear. A counselor’s time may count as program spending, while the payroll system that pays the counselor may be classified as administration. Both are needed for the service to happen.
What a zero-overhead rule changes
When donors insist that every dollar go directly to programs, charities may face pressure to limit the costs they can report as overhead. They can respond by cutting administrative capacity, relying on unpaid labor, or shifting expenses into program budgets where accounting rules allow. Those choices may make a ratio look better without making the organization more effective.
The harder problem is that some costs cannot simply be wished away. If an organization cannot afford experienced staff, reliable data systems, or basic maintenance, it may serve fewer people, lose track of whether programs are working, or struggle to keep services running. A lean budget can be prudent; an artificially starved one can undermine the work it is meant to protect.
Judge the work, not one percentage
Overhead is not proof that a charity is wasteful, just as a low overhead rate is not proof that its programs succeed. Donors can look at what the organization does, whether it can explain its spending, and whether it can show that its services reach their intended beneficiaries.
The practical tradeoff is straightforward: money spent on competent operations is not automatically money diverted from the cause. Sometimes it is what allows the cause to be served reliably at all.