How the “Dutch sandwich” routed profits
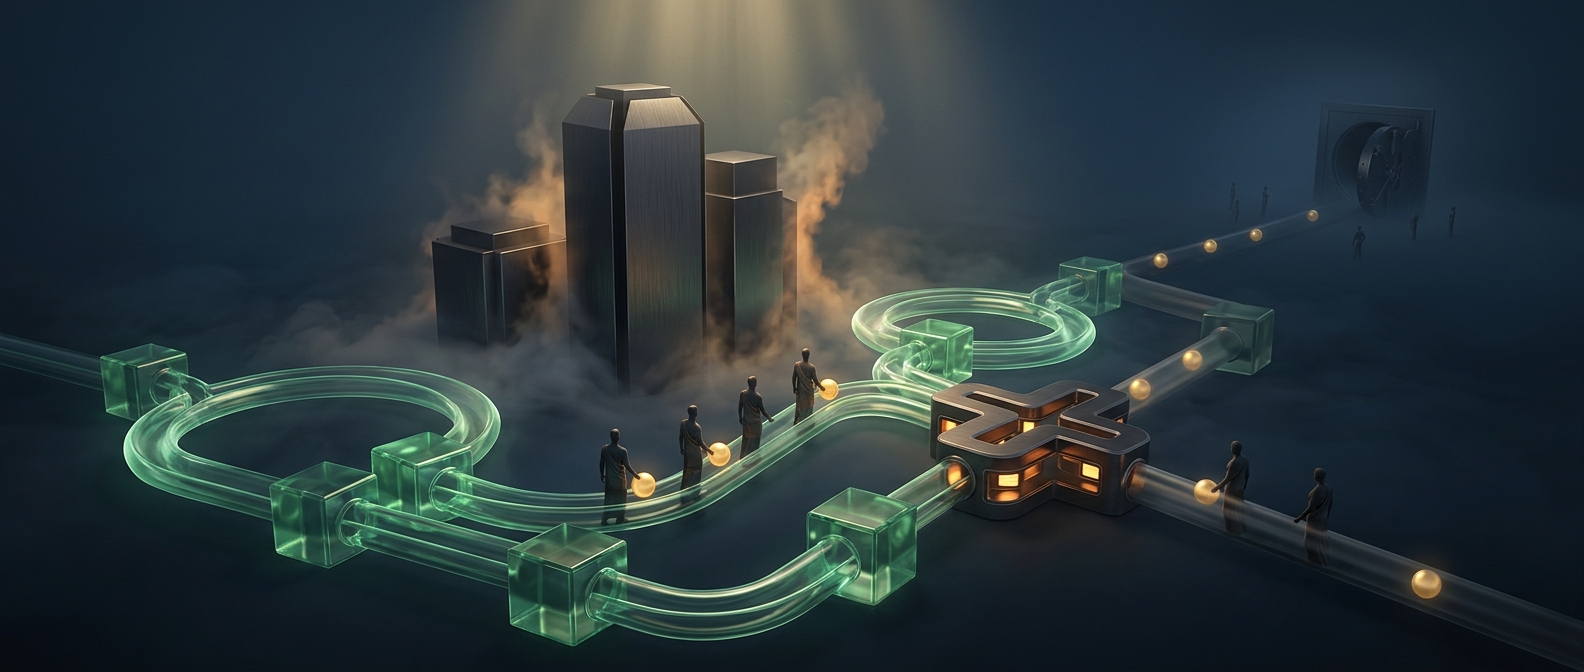
The name describes a chain of subsidiaries, not a special tax in the Netherlands. A company could book income in one country, move it through a Dutch company, and send it onward to a low-tax jurisdiction. The Netherlands served as the middle layer in a structure often paired with Irish subsidiaries and Caribbean destinations.
The mechanism depended on mismatches between national tax systems. Countries set their own rules for where a company’s profits count as earned and how payments between related companies are treated. A payment labeled a royalty—for the right to use software, a brand, or other intellectual property—might be deductible in one place while receiving little tax in another. By routing such payments through subsidiaries, a multinational could shift reported profits away from countries where it sold products or earned revenue.
Why add a Dutch company?
The Dutch entity could act as a conduit: money entered from one subsidiary and passed to another under a separate payment. That extra step could help the overall arrangement fit the rules of the countries involved, including rules governing cross-border payments and withholding taxes. The benefit came from how the rules interacted, rather than from any single country simply declaring the income tax-free.
This made the strategy depend on a carefully arranged corporate map. A company needed subsidiaries with the right legal roles, contracts assigning valuable intellectual property, and payment flows that could be recognized across borders. The structure was most useful to firms whose profits could be tied to assets such as software or trademarks, which can be licensed between related companies.
Why the route lost ground
The arrangement drew scrutiny because profits could end up far from the customers and workers associated with the underlying business. Governments responded by changing rules that had made certain cross-border routes advantageous. As those rules changed, the original structures were phased out or reworked; the broader incentive to place profits where taxes are lower did not disappear.
The memorable point is that the “sandwich” was built from seams between tax codes. Each step could appear ordinary on its own, while the full route sharply reduced the tax due on profits moving across borders.