Why Washington wanted gold out of private hands
In the early 1930s, the United States tied the dollar to gold: the government stood ready to exchange dollars for gold at a fixed official price. During the banking crisis, people and businesses sought gold and cash rather than trusting banks or keeping money on deposit. That drain made it harder for banks to meet withdrawals and constrained the government’s ability to expand the money supply while the economy was collapsing.
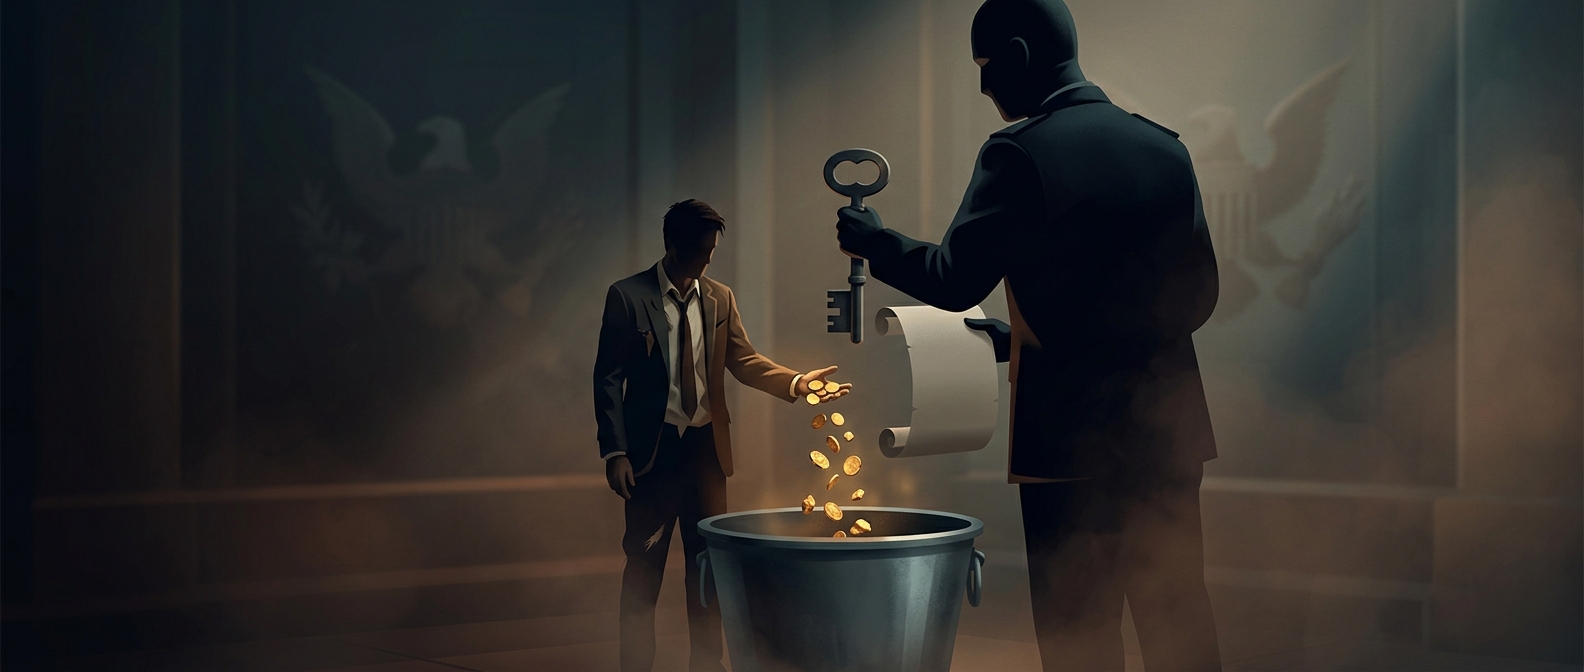
In 1933, President Franklin D. Roosevelt’s administration ordered most people to turn in monetary gold—gold coins, bullion, and gold certificates—to the Federal Reserve or a member bank. The order included exceptions, such as some jewelry and collectible coins, so it did not make every form of gold ownership illegal. But keeping covered gold beyond the deadline could bring criminal penalties.
The price change came after the transfer
The government paid the old official rate, about $20.67 an ounce. After the gold was surrendered, federal policy changed the dollar’s relationship to gold. The Gold Reserve Act of 1934 set the official price at $35 an ounce, reducing the amount of gold represented by a dollar and making more dollars possible against the nation’s gold stock.
That later price was not a payment to the people who had turned in their gold. The gold was held by the government, and the higher official valuation increased the Treasury’s accounting value for it. The policy’s practical aim was to loosen the gold constraint on money and support recovery, not to give former owners a share of the revaluation.
A tradeoff with lasting consequences
The episode shows how a monetary rule can turn private property into a tool of national policy when officials believe the existing system is worsening a crisis. Americans received dollars at the old price, while the government took control of the gold and subsequently valued it more highly. The change helped loosen the link between everyday money and privately held gold—but it also made clear that, in an emergency, the rules governing what money could be exchanged for were not beyond government reach.