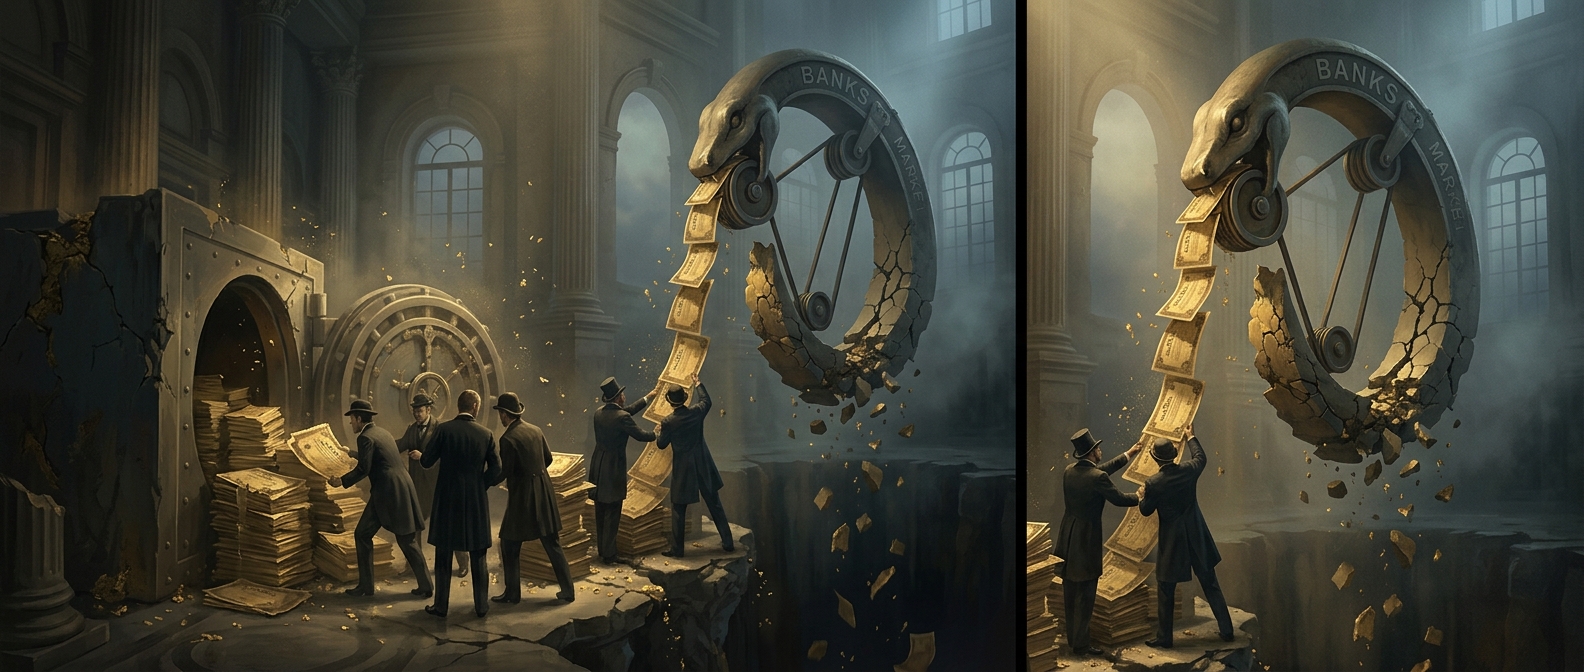
How banks turned their own shares into a promise
For years, Israeli banks helped keep demand for their shares alive by buying them in the market. That support made prices rise or appear steady, encouraging customers to treat bank stock as a dependable place to put savings. The banks were not merely selling shares; they were also helping create the market confidence that made people want to buy them.
The arrangement blurred a crucial distinction: a share price sustained by a company’s own purchases is not the same as a price supported by independent buyers. As long as new customers kept purchasing—and the banks kept stepping in—the system could look stable.
What changed when people wanted out
In 1983, confidence broke and many investors tried to sell at once. A market needs buyers on the other side of each sale. But the banks’ support could not absorb the rush indefinitely. Their share prices plunged, threatening both investors’ savings and the banks’ financial stability.
The episode became known as the Israeli bank share crisis. It exposed how a price that had seemed reassuring depended on banks continually propping it up. When the public stopped buying and started selling, the mechanism meant to sustain confidence became a source of danger.
The cost of keeping the system standing
The government intervened, taking control of almost the entire banking sector to prevent the collapse from spreading through the financial system. That rescue protected the banks from immediate failure, but it also shifted the crisis’s cost onto the state and, ultimately, the public.
The central lesson was not simply that share prices can fall. It was that a bank’s own buying can make its stock look safer than the underlying demand warrants—until the moment customers all ask for their money back at once.