A Guard Dog’s Tax Value Comes From Its Job
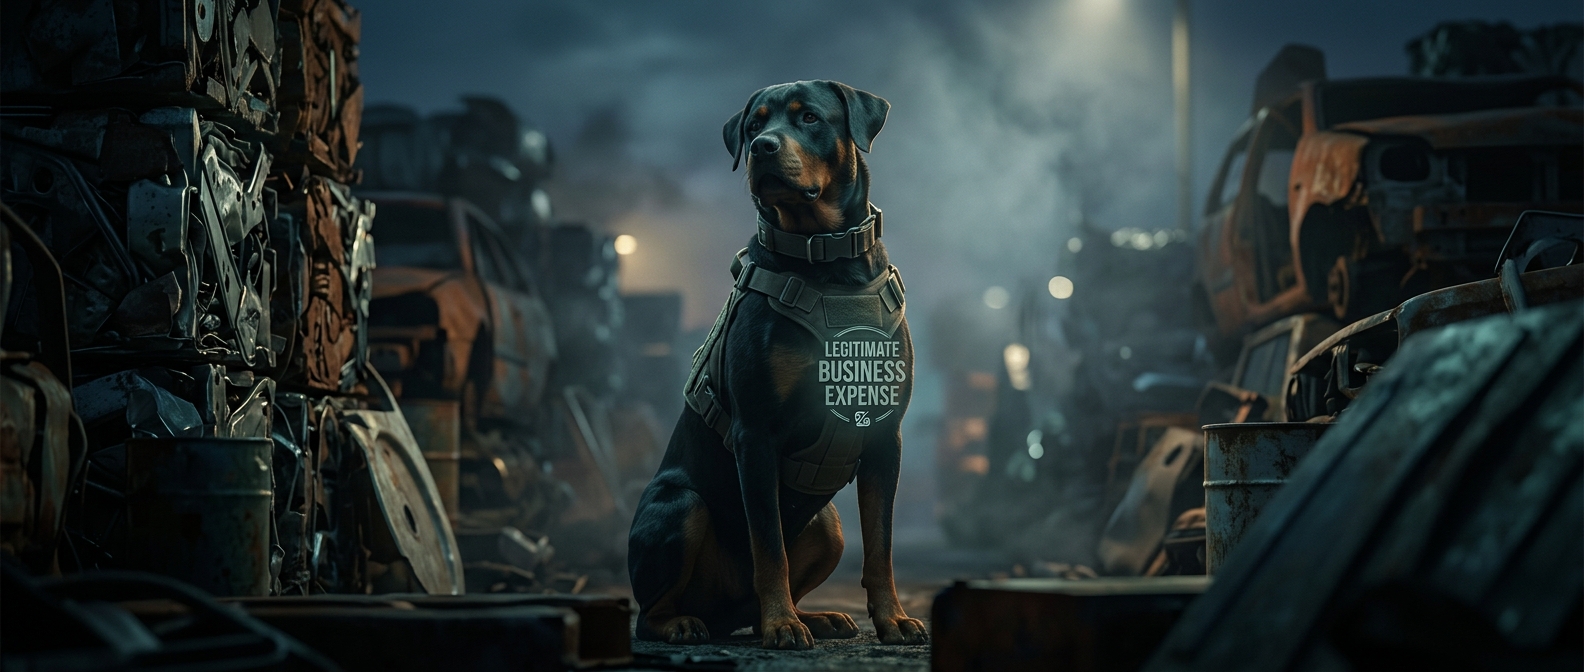
A business can sometimes treat the costs of a dog used to protect its premises as a business expense. The tax logic is functional: the expense must be tied to running the business, rather than simply to owning a pet. A dog’s size or fierce appearance does not establish that connection; its actual role does.
That distinction matters because a deduction generally reduces the income subject to tax—it does not return the full cost of food or veterinary care. If the dog genuinely patrols a shop, warehouse, or other business property, costs associated with that work may be easier to connect to the business than costs for a pet that happens to be nearby.
Shared Use Makes the Case Harder
Many dogs serve more than one purpose. If a dog guards a business but also lives with the owner as a family pet, treating every expense as purely business-related may be difficult to justify. The relevant question is how much of the dog’s care is reasonably connected to protecting the business, not whether the owner can describe it as a guard dog.
Keeping records helps make that connection visible: where the dog is kept, what security role it performs, and which expenses relate to its care. The practical consequence is that the tax treatment follows documented business use, not the dog’s reputation—and a business expense deduction can be limited when personal use is part of the picture.