Why Congress drew a line between banking businesses
In the early 20th century, some banks combined two roles: they accepted deposits and made loans, while also underwriting and trading securities. Underwriting means helping companies issue stocks or bonds to raise money. The arrangement raised a basic concern: a bank might use its influence over depositors’ money to promote securities it was selling, or expose a deposit-taking business to losses from market activity.
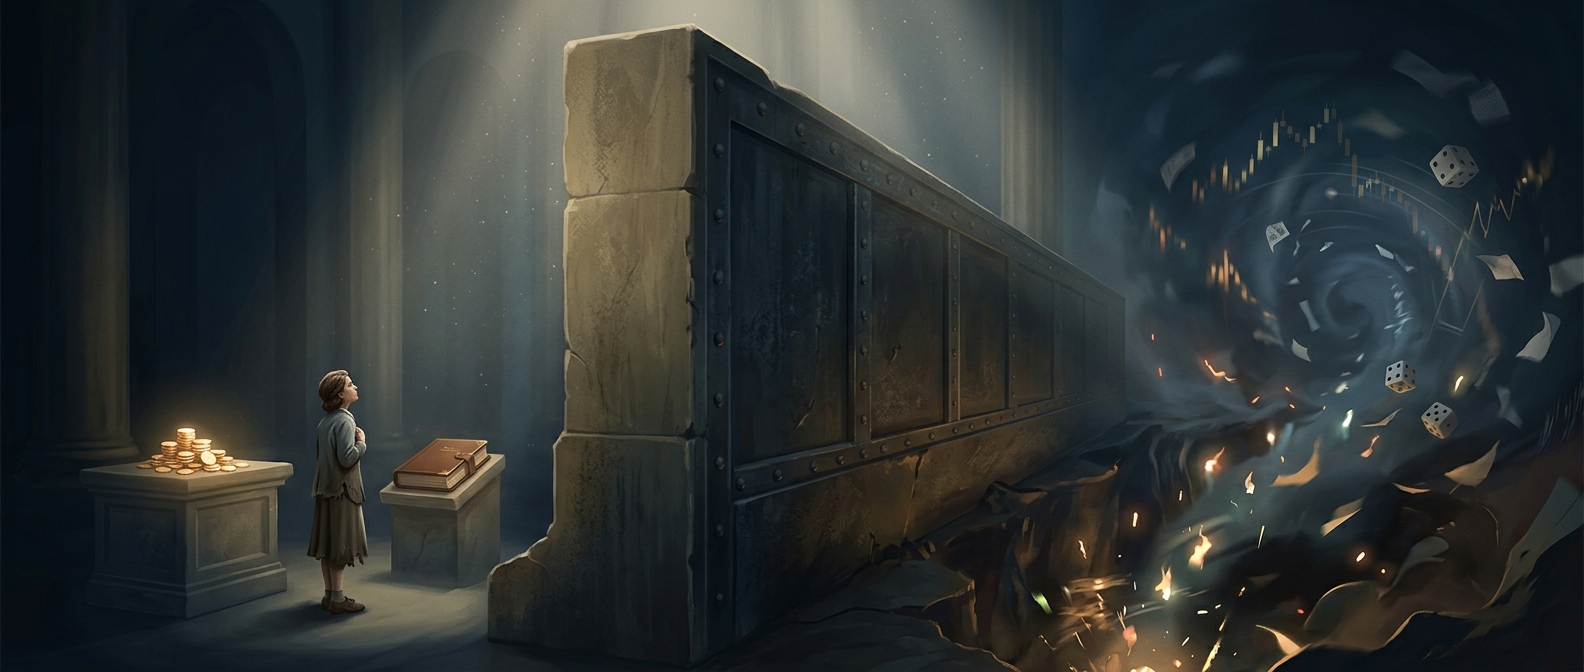
After widespread bank failures during the Great Depression, Congress passed the Banking Act of 1933, commonly called Glass-Steagall. It restricted affiliations between commercial banks and firms engaged in securities underwriting and dealing. The aim was not to prevent banks from taking investment risks altogether; it was to keep those businesses from operating under the same corporate roof as banks whose deposits were federally insured.
What changed in 1999
The Gramm-Leach-Bliley Act repealed key restrictions, allowing commercial banks, securities firms, and insurance companies to affiliate within financial holding companies. Instead of an absolute wall between these kinds of business, a large company could own separate subsidiaries for them.
That structure mattered because it let financial firms offer customers a wider range of services under one corporate group. It also created firms with more interconnected businesses: trouble in one part could affect the rest, and regulators had to oversee risks across a larger organization. The repeal did not erase every rule separating banking activities, nor did it make insured deposits a free pool for speculative trades.
The risk—and the limit of the story
The change is often invoked in discussions of the 2008 financial crisis, but repeal alone does not explain that crisis. Many other practices and vulnerabilities were involved, and the law did not simply authorize banks to gamble depositors’ money without restraint.
The lasting shift was institutional: the United States moved from prohibiting certain combinations of financial businesses to permitting them inside a regulated corporate group. That made the boundary less visible—and made understanding a bank’s risks depend more on looking beyond the bank itself.