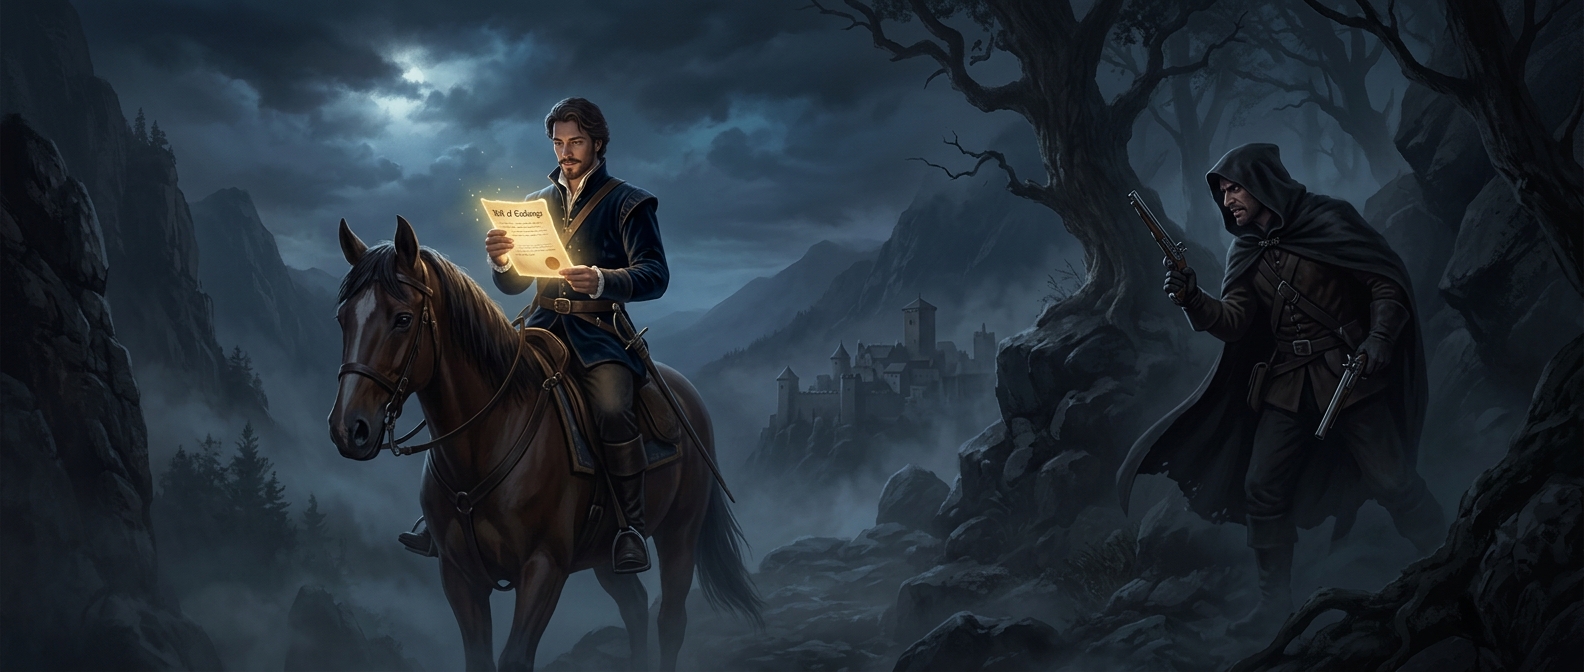
How a promise could travel more safely than gold
A bill of exchange turned a payment into a document. A merchant in one city paid money to a banker or merchant there and received a written order directing a trusted business associate elsewhere to pay the equivalent amount to a named person. Instead of hauling coins across a dangerous road, the merchant carried a claim that could be settled through commercial relationships.
The arrangement depended on trust and records. The local agent had to recognize the order, verify who presented it, and keep accounts with the person or firm that issued it. Merchants could also pass a bill to someone else, allowing it to serve as a means of payment before it was finally redeemed.
The risk changed; it did not vanish
A robber who stopped a traveler might seize cash, but a bill was less useful to a stranger: its value depended on the people and businesses expected to honor it. This reduced the payoff of attacking a merchant carrying funds. It also spared traders the weight and inconvenience of transporting large amounts of coin.
But the paper was not magic protection. It could be lost or stolen, and payment still depended on the issuer and the distant agent being trustworthy and able to pay. Merchants paid for the service, and exchange rates could affect how much the recipient ultimately received. The system replaced one danger—carrying visible wealth—with reliance on a network of credit and reputation.
Trade could move without the treasure
That shift mattered because long-distance commerce often required paying people in different cities. Bills let money be transferred through bookkeeping and business connections rather than by moving the same coins from one place to another. The road still carried the merchant; it no longer had to carry the merchant’s entire fortune.