A Neighborhood Built Its Own Credit Loop
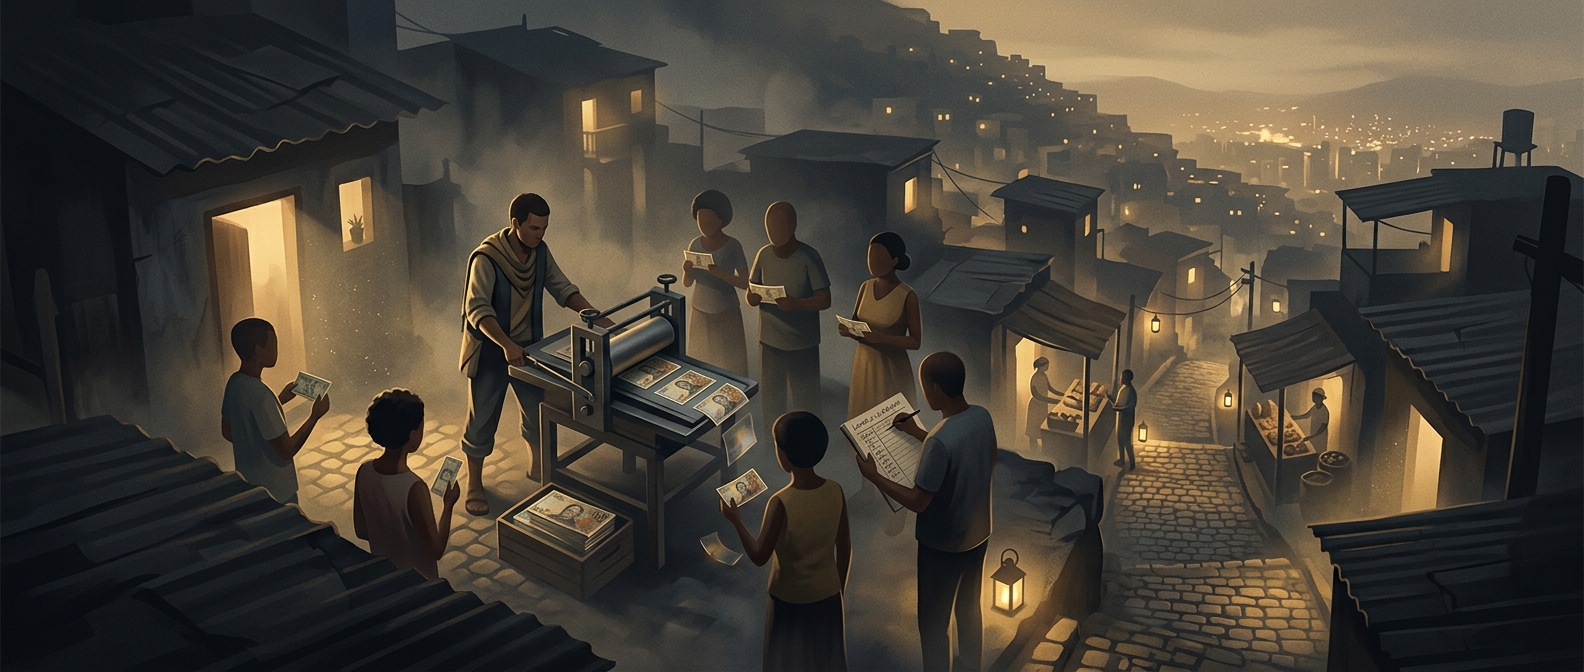
When conventional banks would not lend to residents of Conjunto Palmeiras, a low-income neighborhood in Fortaleza, locals created Banco Palmas in 1998. The bank’s answer was not simply to offer loans: it tried to make sure that money borrowed in the neighborhood would also be spent there.
How the Palma Kept Money Moving Locally
Banco Palmas issued the Palma, a local currency accepted only by participating businesses in the favela. A resident could use it to buy goods nearby, but not take it to a shop across town. That restriction gave local merchants a reason to accept the currency—and gave borrowers a practical way to direct spending toward neighborhood businesses.
The mechanism was a circulation loop. A loan put purchasing power in residents’ hands; their purchases became sales for local shops; and those sales helped keep income and demand within the community. A conventional loan can also support local spending, but the Palma made the intended destination of that spending explicit.
Credit as Local Infrastructure
The arrangement linked access to credit with the neighborhood’s ability to sustain its own businesses. For residents, a loan could mean more than money for an individual purchase: it could help support the shops that made everyday goods available close to home. For merchants, accepting the Palma meant taking part in a system designed to bring customers and spending into the local economy.
Brazil later legally recognized the system. Its central idea was concrete: when money is scarce, a community can try to stretch its impact by keeping it circulating among the people and businesses most likely to spend it nearby.