How a central bank’s bond purchases work
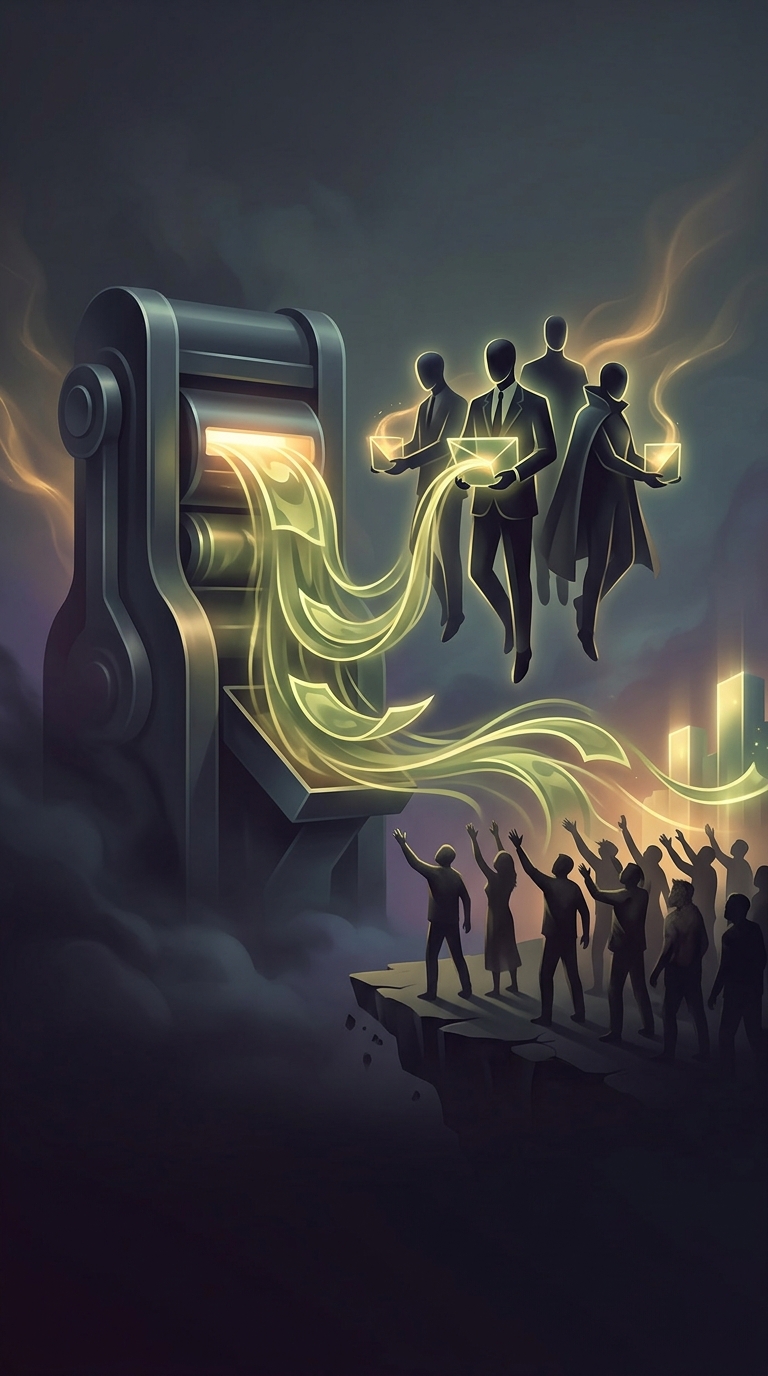
Quantitative easing, or QE, is a way for a central bank to ease financial conditions when cutting its short-term interest rate is no longer enough. The central bank buys longer-term government bonds and sometimes other securities, paying electronically by adding funds to the seller’s bank account. The corresponding increase in bank reserves—money banks hold at the central bank—is created as part of that transaction; it is not a government budget payment to households.
The seller may be a bank, but often is an investor whose bank receives the new deposit. That distinction matters: QE does not automatically turn into loans for businesses and families. Banks still assess whether borrowers are creditworthy, and customers must want to borrow.
Why buying bonds can support the economy
A large, steady buyer raises demand for the securities it purchases. Their prices tend to rise, while their yields—the returns investors can expect—tend to fall. Lower long-term yields can make mortgages and business borrowing cheaper, and can encourage investors to move money into other assets. Central-bank purchases can also signal that short-term rates are likely to stay low, shaping expectations beyond the immediate transaction.
Those channels can ease pressure when markets are strained and help keep credit flowing. But the effect depends on banks, borrowers, and investors responding; creating reserves alone does not guarantee new spending or investment.
Who benefits—and what the tradeoff is
Lower yields can raise the market value of existing bonds, while cheaper borrowing and stronger investor demand can support prices of other assets. People who already own stocks, bonds, or property are therefore positioned to benefit directly from rising valuations. Those without substantial investments may gain less from that channel, even if they benefit indirectly from a stronger economy or improved job prospects.
QE is thus both a market-stabilizing tool and a policy with uneven effects. Its central bank can expand its balance sheet quickly, but it cannot ensure that every newly created bank deposit becomes a loan—or that the resulting gains are shared evenly.