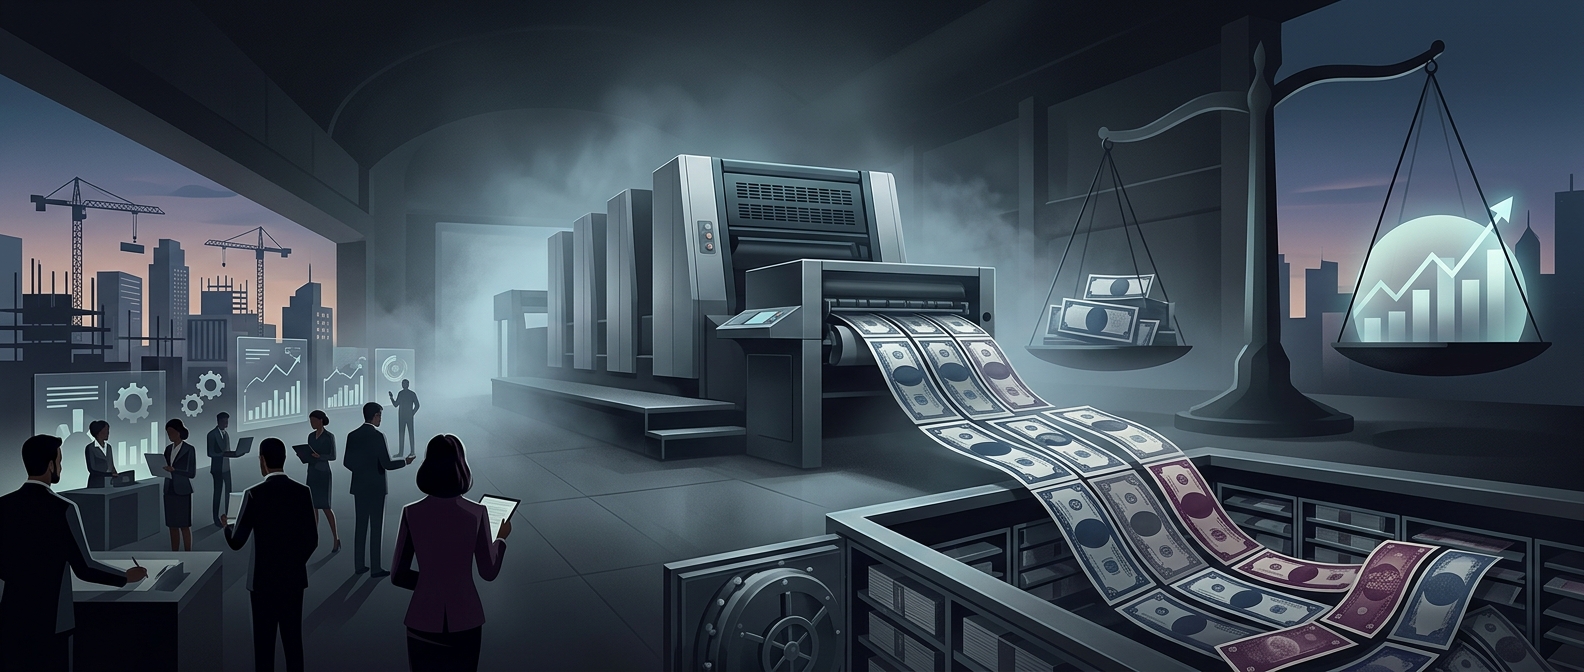
“Printing money” can mean different things
The phrase often refers to a central bank creating electronic money, not producing banknotes. When it buys government bonds or other assets, it typically credits the seller’s bank with reserves—funds banks use to settle payments with one another. Those reserves are not the same as money in a household’s checking account, and a bank cannot simply hand them to a customer to spend at a grocery store.
Spending is the link to consumer prices
For shoppers to feel a price effect, new money generally has to support more spending: households may receive transfers, businesses may borrow and invest, or lower interest rates may encourage purchases. Banks lend when they see willing borrowers and expect repayment; the supply of reserves alone does not guarantee that lending will happen. People and firms may instead save, repay debts, or hold cash, limiting the immediate boost to demand.
Even when spending rises, prices do not automatically rise by the same amount. Businesses can respond to stronger demand by producing more, especially when workers, equipment, and materials are available. Inflationary pressure is more likely when spending grows faster than the economy’s ability to supply goods and services. Then customers compete for limited output, and businesses have more reason to raise prices.
Why the same policy can have different effects
A central bank’s asset purchases may help keep borrowing costs down and support spending, but their effect depends on what households, businesses, banks, and the government do next—and on how much spare capacity the economy has. Money held in the financial system can still matter, for example by changing interest rates or asset prices, without immediately showing up as higher grocery bills. The key question is not simply how much money was created, but whether it adds to demand faster than production can respond.