When a Check Became a Promise
A check normally works because a bank stands behind the chain: the payer’s bank verifies the account and transfers funds to the recipient’s bank. During Ireland’s 1970 bank strike, that routine clearing process was disrupted for months. A check could still be written, but its recipient could not count on quickly depositing it and receiving usable money.
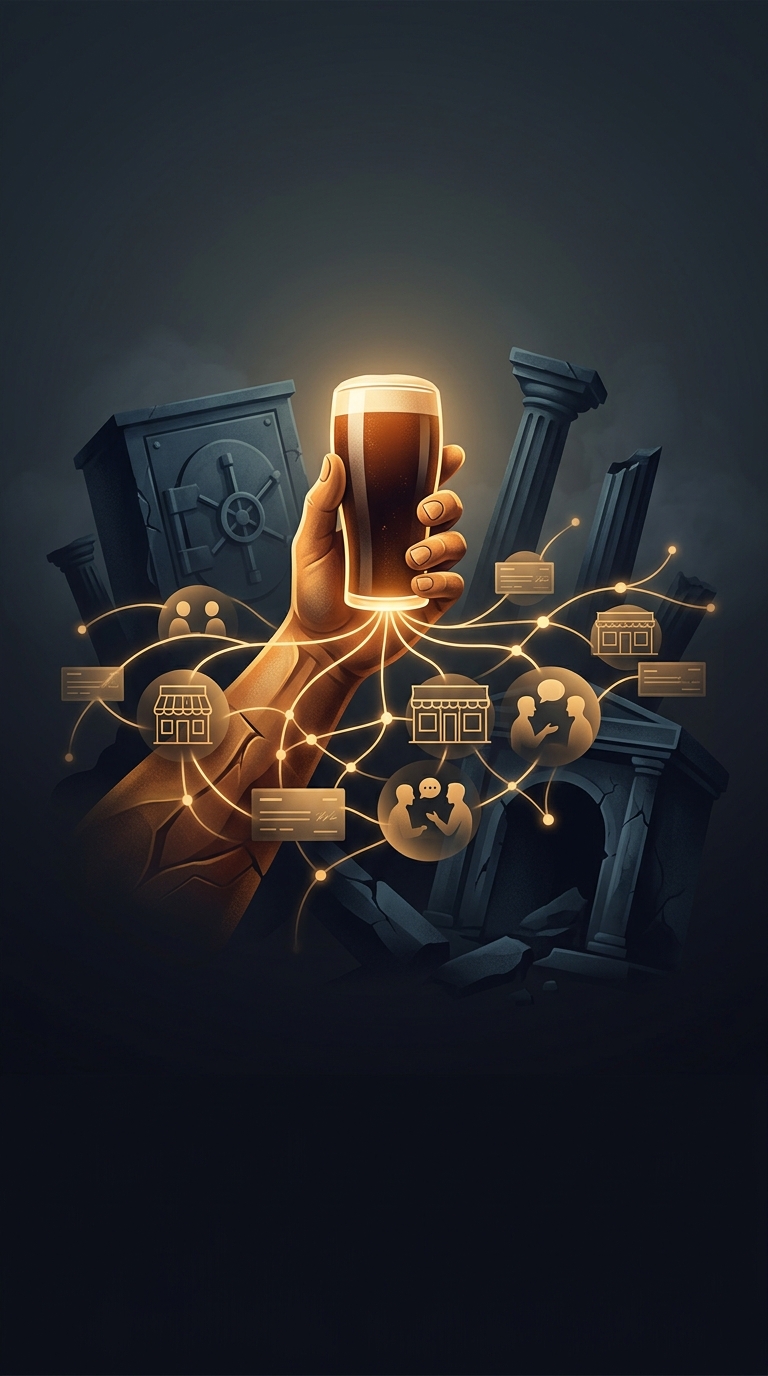
So people treated some checks less like instructions to banks and more like promises between people. A shopkeeper might accept one from a regular customer, then use it to settle a bill with a supplier who trusted the shopkeeper. In effect, the paper could pass along before anyone had confirmed that the original account would pay.
Trust Filled the Gap
This arrangement depended on local knowledge. People were more willing to accept a promise from someone whose business, reputation, and likely future income they could judge than from a stranger. Familiar shops and pubs could extend credit because customers returned, suppliers knew the businesses, and unpaid debts could damage relationships as well as finances.
That trust did not make every check safe. A recipient still risked being left with paper that could not ultimately be honored. The practical question became not only “Is there money in the account?” but “Do I believe this person will be able to pay, and will I be able to pass the promise on?”
Credit Kept Trade Moving
The strike exposed a normally hidden part of everyday commerce: payments rely not just on money, but on a system for confirming and transferring it. When that system stalled, familiar relationships helped people extend short-term credit and keep purchases moving. A neighbor’s credibility could temporarily do work that a bank’s clearing machinery usually does. The checks still needed eventual settlement; trust bought time, not a replacement for the banking system.