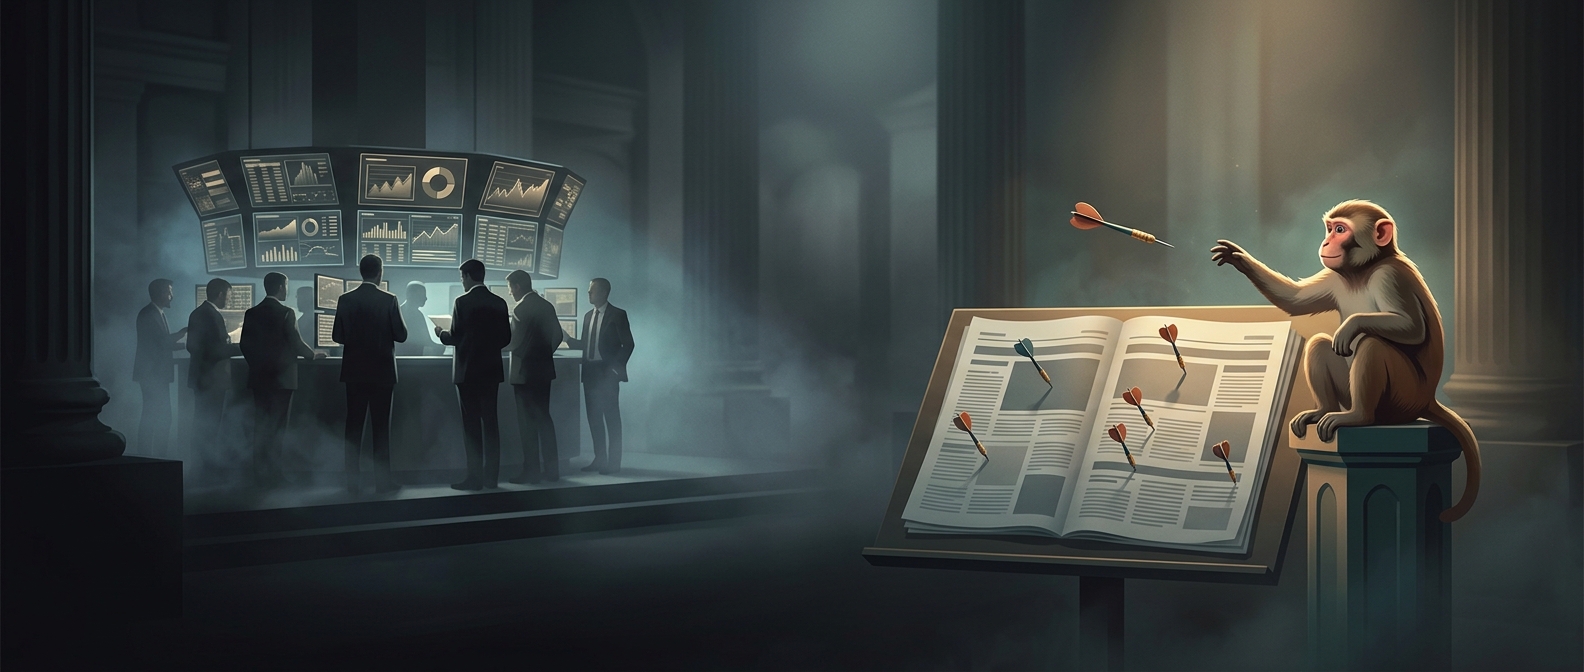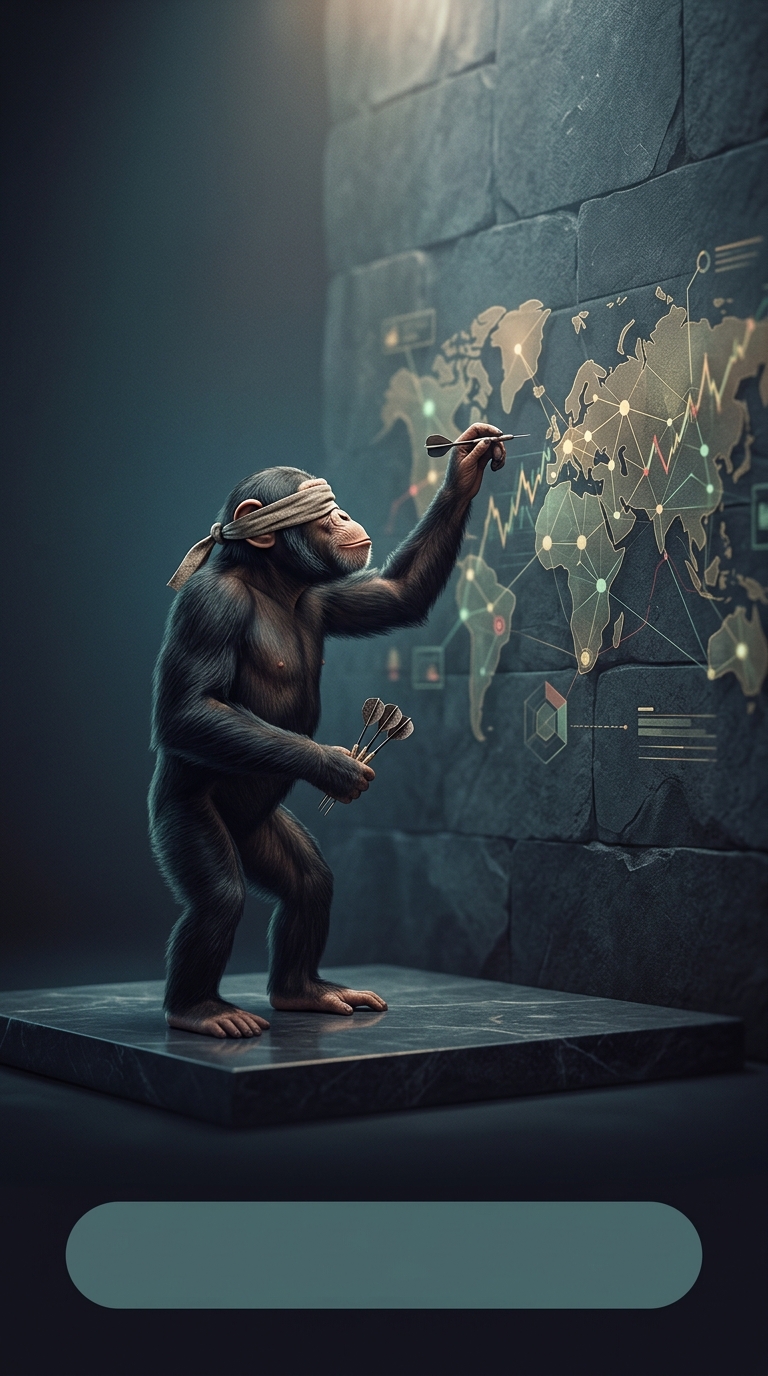
What the dart-throwing monkey is supposed to beat
The target is professional stock pickers: investors who choose individual shares in hopes of doing better than a broad market index. The image is a vivid shorthand for a less amusing possibility—that a random selection of stocks can match or outperform a carefully researched portfolio.
The comparison works because beating the market is harder than simply picking shares that rise. A manager’s portfolio must do better than an appropriate benchmark, such as an index of similar stocks, after accounting for the risk taken and the costs of trading and management.
Why random picks can look surprisingly smart
In a large market, some stocks soar while others slump, and predicting which will happen is difficult. A random portfolio can therefore land on winners by chance. Over a short contest, it may beat an expert’s picks without having any genuine insight; repeat the contest with new stocks or over a longer period, and the result may change.
There is also a built-in hurdle for active managers. Their research and trading have costs, and those expenses reduce what investors keep. An index fund, by contrast, aims to track a market benchmark with relatively little trading. So even a manager who makes reasonably good choices may leave clients with less than the benchmark after fees.
The lesson is about the odds, not a monkey’s skill
The metaphor does not mean that every expert loses to random picks, or that all stock choices are interchangeable. It highlights how difficult it is to identify, in advance, the managers who will keep outperforming after costs. A few may do so; past success alone does not guarantee that they will repeat it.
For ordinary investors, the practical consequence is that paying more for an active strategy makes sense only if its expected advantage is large enough to overcome its costs. The monkey is memorable because it turns that quiet arithmetic into a simple challenge: can the expert’s edge survive fees, chance, and time?