How a local currency tries to keep spending nearby
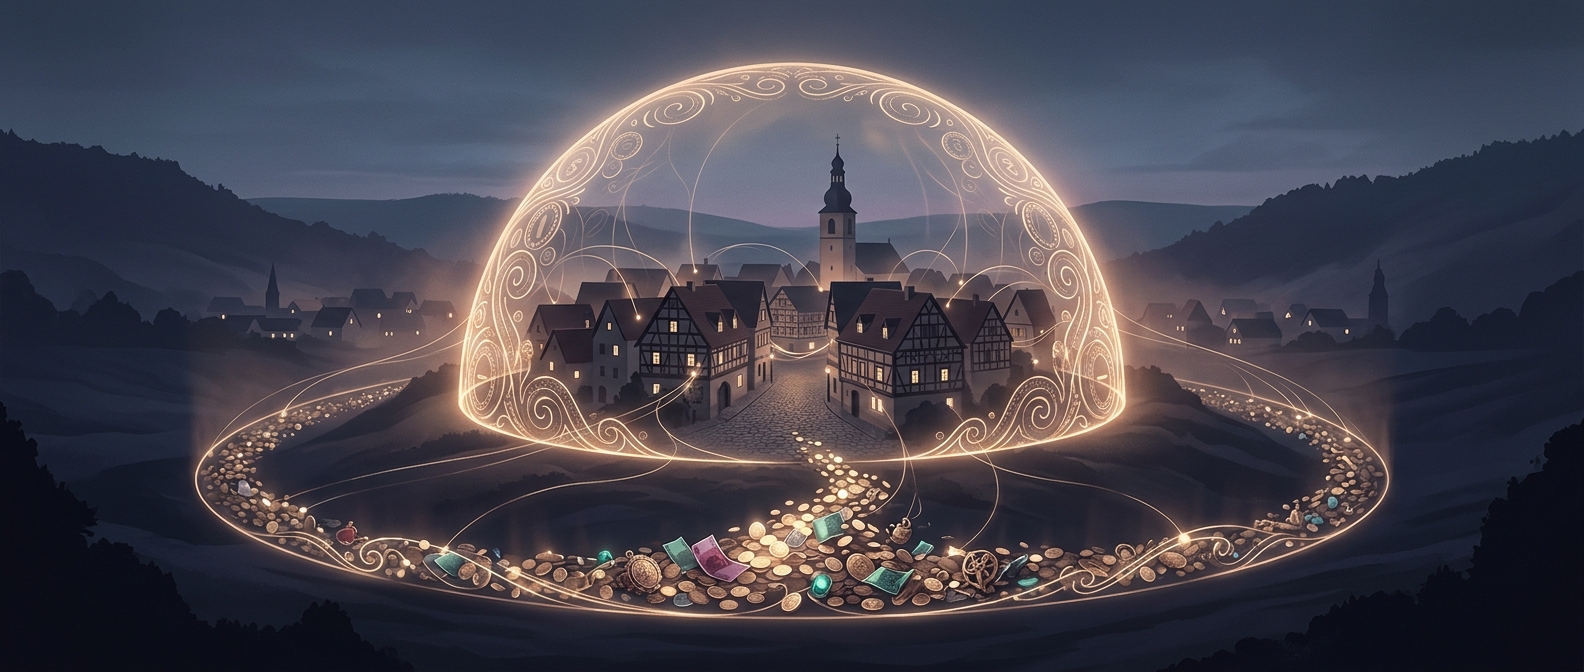
A local currency creates a smaller circuit of exchange alongside the national money system. Participating businesses accept it for purchases, then can spend it with other participating businesses—for supplies, services, or everyday needs. The aim is not simply to give residents another way to pay. It is to make the next destination of a payment more likely to be another local business.
That matters because money often leaves a community when a customer pays a large chain or when a local shop buys goods from far away. A neighborhood currency cannot prevent those flows, but it can encourage a chain of local transactions before money exits. One shop’s revenue becomes another shop’s customer spending.
The network is the real currency
A note has little practical value if few places accept it. The businesses that joined after the 2003 launch supplied the essential infrastructure: each new participant gave customers another place to spend the currency and gave merchants another place to use it. In effect, the project depended on a local network, not just on printing money.
The design also creates a tradeoff. A business may welcome extra local customers, but it needs useful ways to spend what it receives. If its suppliers or workers do not accept the currency, it may have to persuade customers to use it or exchange it through whatever arrangements the system provides. The more connected the participating businesses are, the easier it is for the money to circulate rather than pile up unused.
A nudge, not a sealed economy
A town currency does not make local businesses independent of national markets: they still need outside money for many purchases and obligations. Its more modest purpose is to shape some everyday choices. When a customer pays a neighbor in a currency that another neighbor will accept, the payment carries an invitation to keep the next transaction close to home.