Antwerp’s exchange turned credit into something tradable
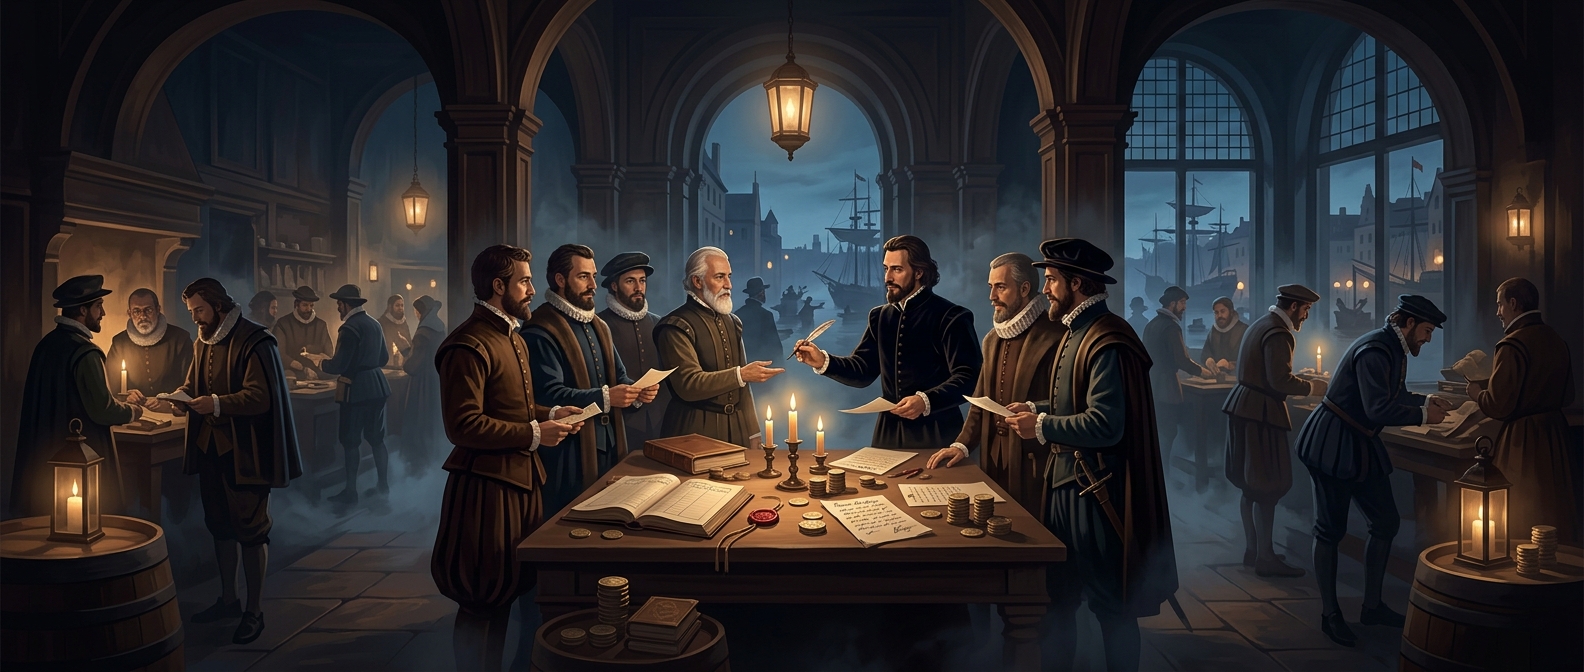
Before a modern bank transfer, a merchant might settle a distant deal with a written promise to pay later. Such a promise—a promissory note—could be passed to someone else, but finding a buyer and agreeing on its value took work. Antwerp’s exchange, which opened in 1531, gave brokers and merchants a regular place to trade these claims alongside municipal bonds, which represented money lent to a city.
The important change was not that people began borrowing. It was that debts could circulate more readily. A holder who needed cash did not always have to wait for the original borrower to repay: the holder could try to sell the claim to another trader. Buyers, meanwhile, could compare obligations and decide what a future payment was worth to them.
A meeting place made promises easier to price
Bringing traders together helped make this process more visible and organized. When many people could offer or seek the same kinds of claims, their negotiations helped establish prices. That gave merchants a way to judge the cost of credit and gave sellers a better chance of finding a buyer. The exchange did not eliminate the risk that a borrower might fail to pay; it made the claims easier to trade despite that risk.
Municipal bonds connected this market to city finances. A city could raise money by borrowing, while investors acquired a claim on repayment. If an investor later wanted to leave the arrangement, the bond could be sold rather than held until maturity. The exchange made a promise of future payment more useful in the present.
That mattered in a commercial hub where business often crossed borders and payment could take time. Antwerp’s exchange helped turn credit from a private arrangement between two parties into something a wider circle of traders could buy, sell, and value—one reason its opening became a landmark in the history of financial markets.